Showing posts with label Libor forward rates. Show all posts

Wednesday, October 30, 2019

QuantLib-Python: Note on ForwardCurve Construction

In this post, we will construct QuantLib ForwardCurve instance and investigate the resulting term structure of discount factors. Python program and Excel can be downloaded from my GitHub page. First, let us assume the following market data containing [A] one cash deposit and three interpolated rates from futures strip.


After completing bootstrapping procedure, we should get [B] simple spot discount factors and [C] simple forward rates. Next, let us implement this scheme in QuantLib. Import QuantLib libraries and create relevant date objects. Then, set forward rates (from [C]), dates and create QuantLib forward curve instance.

import QuantLib as ql
today = ql.Date(30, 10, 2019)
ql.Settings.instance().evaluationDate = today  
settlementDate = ql.TARGET().advance(today, ql.Period(2, ql.Days))

rts = [0.03145, 0.03145, 0.0278373626373627, 0.0253076923076923, 0.0249373626373629]
dts = [settlementDate, ql.Date(1,2,2020), ql.Date(1,5,2020), ql.Date(1,8,2020), ql.Date(1,11,2020)]
c = ql.ForwardCurve(dts, rts, ql.Actual360(), ql.NullCalendar(), ql.BackwardFlat())
df = [c.discount(d) for d in dts]
print(df)

We get the following set of spot discount factors from the curve instance.
[1.0, 0.9919949898918935, 0.9851153255552918, 0.9787646299045335, 0.9725469122728971]
Note, that these are not what we expected to see. "The correct ones" are calculated in the column [B] in the example above. The issue here is, that when constructing ForwardCurve object, the given forward rates inputs are implicitly defined as continuously compounded rates. Assuming we would like to get the same discount factor term structure as in our example above in [B], we need to convert our forward rate inputs from simple to continuously compounded rates. Let us implement this in QuantLib. Convert simple rates to continuous rates. Then, reset forward rates and re-create QuantLib forward curve instance.

for i in range(len(rts) - 1):
    r_simple = ql.InterestRate(rts[i + 1], ql.Actual360(), ql.Simple, ql.Once)
    t = ql.Actual360().yearFraction(dts[i], dts[i + 1])
    r_continuous = r_simple.equivalentRate(ql.Continuous, ql.NoFrequency, t)
    rts[i + 1] = r_continuous.rate()
    
# set rate for the first node
rts[0] = rts[1]
c = ql.ForwardCurve(dts, rts, ql.Actual360(), ql.NullCalendar(), ql.BackwardFlat())
df = [c.discount(d) for d in dts]
print(df)

We get the following "correct" set of spot discount factors from the curve instance.
[1.0, 0.9920268596783518, 0.9851707210231435, 0.9788400520709886, 0.9726415228427708]
Inputs (dates and forward rates) for ForwardCurve object are defined in yellow box in column [E] below.


ForwardCurve object interpolation scheme is backward flat. This means, that for the final period (from 1-Aug-20 to 1-Nov-20), forward rate of 2.48582% will be applied. Implicitly this means, that there is no practical use for the first given forward rate (at the node, where the date is 1-Nov-19). However, this rate has to be defined anyway.

Note, that QuantLib logic of constructing ForwardCurve object is completely correct. One should just be aware of the fact, that input forward rates given are handled implicitly as continuously compounded rates.

Finally, there are some other types of issues concerning forward rate interpolation, which might be worth of knowing when working with ForwardCurve object. These issues are fully explained in this video given by QuantLib lead developer Luigi Ballabio.

As always, thanks for reading this blog.
-Mike

Sunday, October 20, 2019

Python-QuantLib-SciPy: Optimizing Smooth Libor Forward Curve Revisited

One reader was making a remark, that my implementation for curve calibration scheme as presented in here, was not implemented by using QuantLib. As I was re-thinking my implementation, I suddenly remembered that in QuantLib, there are actually several ways to create yield term structures. One such approach is to create yield term structure from a set of given dates and forward rates. Also, VanillaSwap class gives us a direct mechanism for valuing swap transaction by using constructed curve. Bingo. So, this post is re-visiting curve calibration scheme, but this time implemented by using relevant QuantLib-Python library tools.

A few words about utility classes. Convert class will be used for transforming specific in-built data types into specific QuantLib types (Date, Calendar, DayCounter, etc). VanillaSwap class is just a wrapper for corresponding QuantLib.VanillaSwap class. It should be noted, that there is conventional NPV method for requesting swap PV by giving two specific arguments (yield term structure and floating leg index). There is also another method NPV_calibration, which is used for calculating swap PV during calibration process. For this method, input arguments are list of forward rates, list of forward dates and list of initial market rates. From this information, specific yield term structure implementation (QuantLib.ForwardCurve) will be created and used for valuing swap transaction.

import re
import numpy as np
import scipy.optimize as opt
import matplotlib.pyplot as pl
import QuantLib as ql

# utility class for different QuantLib type conversions 
class Convert():
    
    # convert date string ('yyyy-mm-dd') to QuantLib Date object
    def to_date(s):
        monthDictionary = {
            '01': ql.January, '02': ql.February, '03': ql.March,
            '04': ql.April, '05': ql.May, '06': ql.June,
            '07': ql.July, '08': ql.August, '09': ql.September,
            '10': ql.October, '11': ql.November, '12': ql.December
        }
        arr = re.findall(r"[\w']+", s)
        return ql.Date(int(arr[2]), monthDictionary[arr[1]], int(arr[0]))
    
    # convert string to QuantLib businessdayconvention enumerator
    def to_businessDayConvention(s):
        if (s.upper() == 'FOLLOWING'): return ql.Following
        if (s.upper() == 'MODIFIEDFOLLOWING'): return ql.ModifiedFollowing
        if (s.upper() == 'PRECEDING'): return ql.Preceding
        if (s.upper() == 'MODIFIEDPRECEDING'): return ql.ModifiedPreceding
        if (s.upper() == 'UNADJUSTED'): return ql.Unadjusted
        
    # convert string to QuantLib calendar object
    def to_calendar(s):
        if (s.upper() == 'TARGET'): return ql.TARGET()
        if (s.upper() == 'UNITEDSTATES'): return ql.UnitedStates()
        if (s.upper() == 'UNITEDKINGDOM'): return ql.UnitedKingdom()
        # TODO: add new calendar here
        
    # convert string to QuantLib swap type enumerator
    def to_swapType(s):
        if (s.upper() == 'PAYER'): return ql.VanillaSwap.Payer
        if (s.upper() == 'RECEIVER'): return ql.VanillaSwap.Receiver
        
    # convert string to QuantLib frequency enumerator
    def to_frequency(s):
        if (s.upper() == 'DAILY'): return ql.Daily
        if (s.upper() == 'WEEKLY'): return ql.Weekly
        if (s.upper() == 'MONTHLY'): return ql.Monthly
        if (s.upper() == 'QUARTERLY'): return ql.Quarterly
        if (s.upper() == 'SEMIANNUAL'): return ql.Semiannual
        if (s.upper() == 'ANNUAL'): return ql.Annual

    # convert string to QuantLib date generation rule enumerator
    def to_dateGenerationRule(s):
        if (s.upper() == 'BACKWARD'): return ql.DateGeneration.Backward
        if (s.upper() == 'FORWARD'): return ql.DateGeneration.Forward
        # TODO: add new date generation rule here

    # convert string to QuantLib day counter object
    def to_dayCounter(s):
        if (s.upper() == 'ACTUAL360'): return ql.Actual360()
        if (s.upper() == 'ACTUAL365FIXED'): return ql.Actual365Fixed()
        if (s.upper() == 'ACTUALACTUAL'): return ql.ActualActual()
        if (s.upper() == 'ACTUAL365NOLEAP'): return ql.Actual365NoLeap()
        if (s.upper() == 'BUSINESS252'): return ql.Business252()
        if (s.upper() == 'ONEDAYCOUNTER'): return ql.OneDayCounter()
        if (s.upper() == 'SIMPLEDAYCOUNTER'): return ql.SimpleDayCounter()
        if (s.upper() == 'THIRTY360'): return ql.Thirty360()
        
    # convert string (ex.'USDLibor.3M') to QuantLib ibor index object
    # note: forwarding term structure has to be linked to index object separately
    def to_iborIndex(s):
        s = s.split('.')
        if(s[0].upper() == 'USDLIBOR'): return ql.USDLibor(ql.Period(s[1]))
        if(s[0].upper() == 'EURIBOR'): return ql.Euribor(ql.Period(s[1]))  

class VanillaSwap(object):
    
    def __init__(self, ID, swapType, nominal, startDate, maturityDate, fixedLegFrequency, 
        fixedLegCalendar, fixedLegConvention, fixedLegDateGenerationRule, fixedLegRate, fixedLegDayCount,
        fixedLegEndOfMonth, floatingLegFrequency, floatingLegCalendar, floatingLegConvention, 
        floatingLegDateGenerationRule, floatingLegSpread, floatingLegDayCount, 
        floatingLegEndOfMonth, floatingLegIborIndex):

        # create member data, convert all required QuantLib types
        self.ID = str(ID)
        self.swapType = Convert.to_swapType(swapType)
        self.nominal = float(nominal)
        self.startDate = Convert.to_date(startDate)
        self.maturityDate = Convert.to_date(maturityDate)
        self.fixedLegFrequency = ql.Period(Convert.to_frequency(fixedLegFrequency))
        self.fixedLegCalendar = Convert.to_calendar(fixedLegCalendar)
        self.fixedLegConvention = Convert.to_businessDayConvention(fixedLegConvention)
        self.fixedLegDateGenerationRule = Convert.to_dateGenerationRule(fixedLegDateGenerationRule)
        self.fixedLegRate = float(fixedLegRate)
        self.fixedLegDayCount = Convert.to_dayCounter(fixedLegDayCount)
        self.fixedLegEndOfMonth = bool(fixedLegEndOfMonth)
        self.floatingLegFrequency = ql.Period(Convert.to_frequency(floatingLegFrequency))
        self.floatingLegCalendar = Convert.to_calendar(floatingLegCalendar)
        self.floatingLegConvention = Convert.to_businessDayConvention(floatingLegConvention)
        self.floatingLegDateGenerationRule = Convert.to_dateGenerationRule(floatingLegDateGenerationRule)
        self.floatingLegSpread = float(floatingLegSpread)
        self.floatingLegDayCount = Convert.to_dayCounter(floatingLegDayCount)
        self.floatingLegEndOfMonth = bool(floatingLegEndOfMonth)
        self.floatingLegIborIndex = Convert.to_iborIndex(floatingLegIborIndex)

        # create fixed leg schedule
        self.fixedLegSchedule = ql.Schedule(
            self.startDate, 
            self.maturityDate,
            self.fixedLegFrequency, 
            self.fixedLegCalendar, 
            self.fixedLegConvention,
            self.fixedLegConvention,
            self.fixedLegDateGenerationRule,
            self.fixedLegEndOfMonth)
        
        # create floating leg schedule
        self.floatingLegSchedule = ql.Schedule(
            self.startDate, 
            self.maturityDate,
            self.floatingLegFrequency, 
            self.floatingLegCalendar, 
            self.floatingLegConvention,
            self.floatingLegConvention,
            self.floatingLegDateGenerationRule,
            self.floatingLegEndOfMonth)

    # NPV method used for specific calibration purposes
    # x = list of forward rates
    # args: 0 = list of forward dates, 1 = list of market rates        
    def NPV_calibration(self, x, args):
        # concatenate given market rates and given forward rates
        x = np.concatenate([args[1], x])
        
        # create QuantLib yield term structure object
        # from a given set of forward rates and dates
        curve = ql.YieldTermStructureHandle(ql.ForwardCurve(args[0], x, 
            self.floatingLegDayCount, self.floatingLegCalendar))        

        # set forwarding term structure to floating leg index
        self.floatingLegIborIndex = self.floatingLegIborIndex.clone(curve) 
        
        # create vanilla interest rate swap
        self.instrument = ql.VanillaSwap(
            self.swapType, 
            self.nominal, 
            self.fixedLegSchedule, 
            self.fixedLegRate, 
            self.fixedLegDayCount, 
            self.floatingLegSchedule,
            self.floatingLegIborIndex,
            self.floatingLegSpread, 
            self.floatingLegDayCount)
        
        # pair instrument with pricing engine, request PV
        self.instrument.setPricingEngine(ql.DiscountingSwapEngine(curve))
        return self.instrument.NPV()
    
    # NPV method used for general pricing purposes
    def NPV(self, yieldTermStructureHandle, floatingLegIborIndex):
        # set forwarding term structure to floating leg index
        self.floatingLegIborIndex = floatingLegIborIndex.clone(yieldTermStructureHandle)
        
        # create vanilla interest rate swap
        self.instrument = ql.VanillaSwap(
            self.swapType, 
            self.nominal, 
            self.fixedLegSchedule, 
            self.fixedLegRate, 
            self.fixedLegDayCount, 
            self.floatingLegSchedule,
            self.floatingLegIborIndex,
            self.floatingLegSpread, 
            self.floatingLegDayCount)
        
        # pair instrument with pricing engine, request PV
        self.instrument.setPricingEngine(ql.DiscountingSwapEngine(yieldTermStructureHandle))
        return self.instrument.NPV()

ObjectiveFunction is used for minimization process for calculating sum of squared errors of all adjacent forward rates. Maximum smoothness of the curve will be achieved as a result of this minimization.

# objective function calculates sum of squared errors of all decision variables
# x = list of forward rates
# args: 0 = list of market rates data, 1 = scaling factor
def ObjectiveFunction(x, args):
    # concatenate given market rates and forward rates
    x = np.concatenate([args[0], x])
    return np.sum(np.power(np.diff(x), 2) * args[1])

The actual program flow will start by creating a set of vanilla interest rate swap objects (VanillaSwap) into list.

# dynamic data parts for set of vanilla swaps 
swapIDs = ['2Y', '3Y', '4Y', '5Y', '6Y', '7Y', '8Y', '9Y', '10Y', '12Y', '15Y', '20Y', '25Y', '30Y']
maturities = ['2010-02-08', '2011-02-07', '2012-02-06', '2013-02-06', '2014-02-06', '2015-02-06', '2016-02-08', 
    '2017-02-06', '2018-02-06', '2020-02-06', '2023-02-06', '2028-02-07', '2033-02-07', '2038-02-08']
swapRates = [0.02795, 0.03035, 0.03275, 0.03505, 0.03715, 0.03885, 0.04025, 0.04155, 0.04265, 0.04435, 
    0.04615, 0.04755, 0.04805, 0.04815]

# create vanilla swap transaction objects into list
swaps = [VanillaSwap(swapID, 'Payer', 1000000, '2008-02-06', maturity, 'Annual', 
    'Target', 'ModifiedFollowing', 'Backward', swapRate, 'Actual360', False, 'Quarterly', 
    'Target', 'ModifiedFollowing', 'Backward', 0.0, 'Actual360', False, 'USDLibor.3M')
    for swapID, maturity, swapRate in zip(swapIDs, maturities, swapRates)]

Next, the program will initialize the actual market data (to be used in forward curve), starting values for forward curve, set of dates for forward curve, optimization constraints and the actual optimization model.

# take initial forward rates from market data, set initial guesses and scaling factor for objective function
initialMarketData = np.array([0.03145, 0.0279275, 0.0253077, 0.0249374])
initialForwardGuesses = np.full(117, 0.02)
scalingFactor = 1000000.0

# create relevant QuantLib dates
today = ql.Date(4, 2, 2008)
ql.Settings.instance().evaluationDate = today  
settlementDate = ql.TARGET().advance(today, ql.Period(2, ql.Days))

# create set of dates for forward curve
dates = list(ql.Schedule(settlementDate, ql.Date(6, 2, 2038), ql.Period(ql.Quarterly), ql.TARGET(),
    ql.ModifiedFollowing, ql.ModifiedFollowing, ql.DateGeneration.Backward, False))

# create constraints for optimization model
swapConstraints = tuple([{'type': 'eq', 'fun': swap.NPV_calibration, 'args': [[dates, initialMarketData]]} for swap in swaps])

# create and execute scipy minimization model
model = opt.minimize(ObjectiveFunction, initialForwardGuesses, args = ([initialMarketData, scalingFactor]), 
    method = 'SLSQP', options = {'maxiter': 500}, constraints = swapConstraints)

After processing optimization model, the actual calibrated forward rates can be requested from the model. Next part of the program will just plot the calibrated forward term structure.

# extract calibrated forward rates, create times and plot term structure
forwards = np.concatenate([initialMarketData, model.x])
times = np.array([ql.Actual360().yearFraction(settlementDate, date) for date in dates])
pl.plot(times, forwards)
pl.show()


Final part of the program will create QuantLib yield term structure (QuantLib.ForwardCurve) and re-values our initial set of swap transactions. All swaps will be priced to zero at inception date.

# create new QuantLib curve from calibrated forward rates
curve = ql.YieldTermStructureHandle(ql.ForwardCurve(dates, forwards, ql.Actual360(), ql.TARGET()))

# value initial set of vanilla swaps using new QuantLib valuation curve
# all swaps will be priced to zero at inception date
for swap in swaps:
    index = ql.USDLibor(ql.Period(3, ql.Months), curve)
    pv = swap.NPV(curve, index)
    print(swap.ID, '{0:.5f}'.format(pv))

It should be noted, that by utilizing calibration scheme presented in this post, valuation curves (yield term structures) for QuantLib for all currencies and for all different basis can be constructed (assuming the relevant market data exists). Next logical step would be to implement similar scheme for calibrating valuation curves for QuantLib for cross-currency cases and within collateralized world.

Complete program can be downloaded from my GitHub page. Example data has been taken from chapter three within excellent book by Richard Flavell. Finally, thanks again for reading this blog.
-Mike

Saturday, June 4, 2016

Excel/VBA : Optimizing smooth OIS-adjusted Libor forward curve using Solver

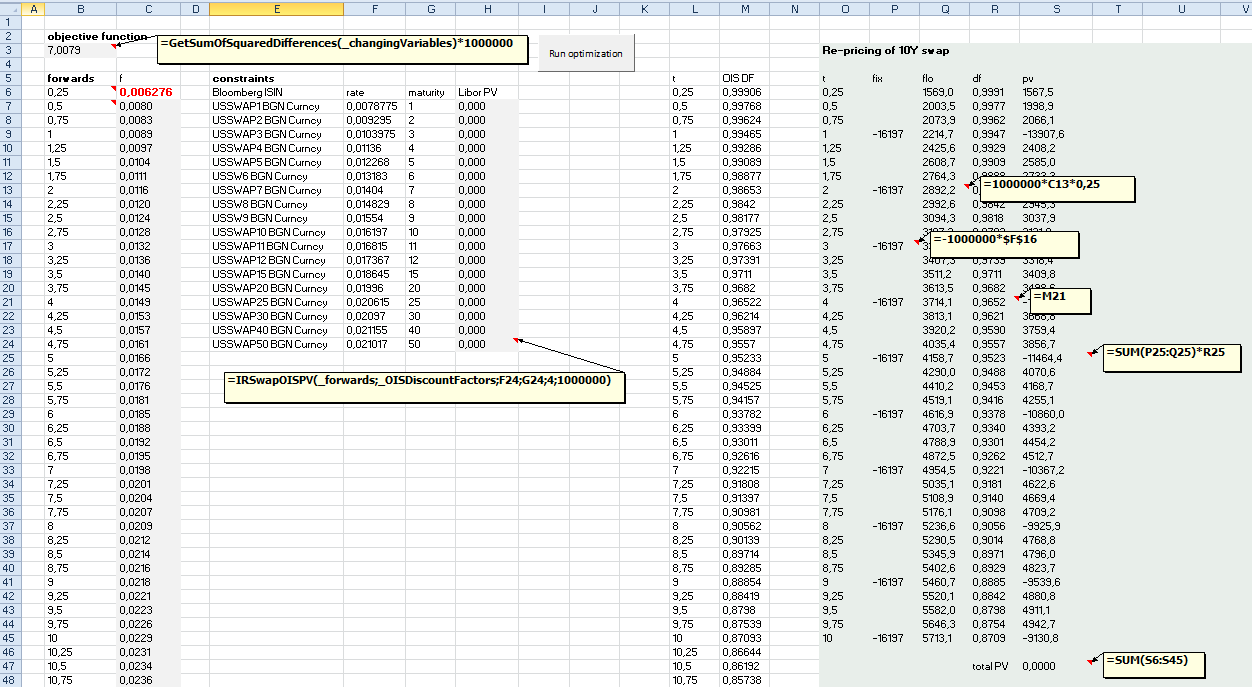
Optimization for Libor forward curve has been presented in this blog post. This time, we will adjust the presented optimization procedure in such way, that OIS-adjusted Libor forward rates are going to be solved for a given fixed set of swap rates and OIS discount factors.

In a nutshell, justification for OIS-adjusted forward rates is the following :

  • In the "old world", we first bootstrapped Libor zero-coupon curve, from which we calculated Libor discount factors and Libor forward rates (for constructing floating leg coupons) at the same time. Only one curve was ever needed to accomplish this procedure. 
  • In the "new world", since all swap cash flows are discounted using OIS discount factors and par swap rates are still used for constructing swap fixed leg cash flows, forward rates (OIS-adjusted Libor forward rates) have to be slightly adjusted, in order to equate present value of all swap cash flows back to be zero.
All the relevant issues have been clearly explained in this research paper by Barclays.

Screenshots below are showing required Excel worksheet setups along with optimized OIS-adjusted Libor forward curve and required additions to existing VBA program needed to perform this optimization task. In order to validate the optimized OIS-adjusted Libor forward curve, a 10-year vanilla swap has been re-priced using optimized OIS-adjusted Libor forward rates and given set of fixed OIS discount factors.

When setting up VBA program, first implement the program presented in this blog post. After this, add two new functions (IRSwapOISPV, linearInterpolation) presented below into module XLSFunctions. Finally, remember to include references to Solver and Microsoft Scripting Runtime libraries.

Thanks for reading this blog.
-Mike


Public Function IRSwapOISPV(ByRef forwards As Excel.Range, ByRef OISDF As Excel.Range, ByVal swapRate As Double, _
ByVal yearsToMaturity As Integer, ByVal floatingLegPaymentFrequency As Integer, ByVal notional As Double) As Double
    '
    ' PV (fixed payer swap) = -swapRate * Q_fixed + Q_float
    ' where Q_fixed is sumproduct of fixed leg OIS discount factors and corresponding time accrual factors
    ' and Q_float is sumproduct of adjusted libor forward rates, OIS discount factors and corresponding time accrual factors
    ' assumption : fixed leg is always paid annually
    ' since fixed leg is paid annually and maturity is always integer, time accrual factor will always be exactly 1.0
    Dim f As Variant: f = forwards.Value2
    Dim DF As Variant: DF = OISDF.Value2
    Dim Q_fixed As Double
    Dim Q_float As Double
    Dim floatingLegTenor As Double: floatingLegTenor = 1 / CDbl(floatingLegPaymentFrequency)
    Dim nextFixedLegCouponDate As Integer: nextFixedLegCouponDate = 1
    Dim currentTimePoint As Double: currentTimePoint = CDbl(0)
    '
    Dim i As Integer
    For i = 1 To (yearsToMaturity * floatingLegPaymentFrequency)
        currentTimePoint = currentTimePoint + floatingLegTenor
        '
        ' update floating leg Q
        Q_float = Q_float + f(i, 1) * linearInterpolation(currentTimePoint, OISDF.Value2) * floatingLegTenor
        '
        ' update fixed leg Q, if current time point is coupon payment date
        If ((currentTimePoint - CDbl(nextFixedLegCouponDate)) = 0) Then
            Q_fixed = Q_fixed + linearInterpolation(currentTimePoint, OISDF.Value2)
            nextFixedLegCouponDate = nextFixedLegCouponDate + 1
        End If
    Next i
    IRSwapOISPV = (-swapRate * Q_fixed + Q_float) * notional
End Function
'
Public Function linearInterpolation(ByVal maturity As Double, ByRef curve As Variant) As Double
    '
    ' read range into Nx2 array
    Dim r As Variant: r = curve
    '
    Dim n As Integer: n = UBound(r, 1)
    '
    ' boundary checkings
    If ((r(LBound(r, 1), 1)) > maturity) Then linearInterpolation = r(LBound(r, 1), 2): Exit Function
    If ((r(UBound(r, 1), 1)) < maturity) Then linearInterpolation = r(UBound(r, 1), 2): Exit Function
    '
    Dim i As Long
    For i = 1 To n
        If ((r(i, 1) <= maturity) And (r(i + 1, 1) >= maturity)) Then
            '
            Dim y0 As Double: y0 = r(i, 2)
            Dim y1 As Double: y1 = r(i + 1, 2)
            Dim x0 As Double: x0 = r(i, 1)
            Dim x1 As Double: x1 = r(i + 1, 1)
            '
            linearInterpolation = y0 + (y1 - y0) * ((maturity - x0) / (x1 - x0))
            Exit For
        End If
    Next i
End Function
'

Wednesday, May 18, 2016

Excel/VBA : Optimizing smooth Libor forward curve using Solver

In order to value fixed income derivatives cash flows, relevant forward rates and discount factors have to be defined from bootstrapped zero-coupon curve. In a Libor world, we use cash and FRA contracts (or futures contracts) in a short-end of the curve, while in a long-end of the curve we use relevant swap contracts. Let us assume for a moment, that we bootstrap zero-coupon curve, in order to define those forward rates and discount factors on a quarterly basis. While bootstrapping usually gives a smooth curve for a short-end of the curve, it will usually fail to do this for a long-end of the curve. This happens, because there is no relevant swap contracts available in a long-end of the curve and hereby, we need to do a lot of interpolation in a long-end of the curve for swaps. The resulting forward curve then looks like a chain of waterfalls.

This time, I wanted to present a cool way to solve those forward rates by using numerical optimization scheme. The topic itself has been thoroughly covered in chapter three in excellent book by Richard Flavell. In a nutshell, we first define the shortest end of the curve (using cash and forwards) and then we just guess the rest of the forward rates. After this, we minimize sum of squared differences between adjacent forward rates, subject to constraints. In this case, constraints are present values of swaps, which by definition will be zero. When this optimization task has been performed, the resulting forward curve will successfully re-price the current swap market.

In Excel worksheet, there has to be three named ranges to be used by VBA program:
  • Objective function (sum of squared differences between adjacent forward rates)
  • Constraints (swap PV for each swap contract used)
  • Decision variables (forward rates to be solved)

Screenshots below are showing required Excel worksheet setups along with optimized Libor forward curve, corresponding capture of Bloomberg smoothed forward curve and the actual VBA program needed to perform optimization task. Note, that for this example, I have been defining only the first 3-month Libor spot rate fixing. The rest of the forward rates are going to be solved. When setting up VBA program, remember to include references to Solver and Microsoft Scripting Runtime libraries.

Finally, thanks for reading my blog.
-Mike


' Worksheet : Libor
Option Explicit
'
Private Sub btnSolveLibor_Click()
    '
    ' define Excel ranges for objective function, decision variables and constraints
    Dim objectiveFunction As Range: Set objectiveFunction = Range("_objectiveFunction")
    Dim changingVariables As Range: Set changingVariables = Range("_changingVariables")
    Dim constraints As Range: Set constraints = Range("_constraints")
    '
    ' create parameter wrapper
    ' for objective function, decision variables and constraints, address of range is needed
    Dim parameters As New Scripting.Dictionary
    parameters.Add PRM.objectiveFunction, CStr(objectiveFunction.Address)
    parameters.Add PRM.changingVariables, CStr(changingVariables.Address)
    parameters.Add PRM.constraints, CStr(constraints.Address)
    parameters.Add PRM.maxMinVal, CInt(2) ' max=1, min=2, valueof=3
    parameters.Add PRM.userFinish, CBool(True)
    parameters.Add PRM.assumeNonNegative, CBool(False)
    parameters.Add PRM.relation, CInt(2) ' lessOrEqual=1, equal=2, greaterOrEqual=3
    parameters.Add PRM.formulaText, CStr("0.0")
    '
    ' create instance of constrained optimization model implementation
    Dim xlSolver As ISolver: Set xlSolver = New ConstrainedOptimization
    xlSolver.solve parameters
    '
    ' release objects
    Set xlSolver = Nothing
    Set parameters = Nothing
End Sub
'
'
'
'
'
' Module : Enumerators
Option Explicit
'
' enumerator needed for parameter wrapper
Public Enum PRM
    objectiveFunction = 1
    maxMinVal = 2
    valueOf = 3
    changingVariables = 4
    userFinish = 5
    assumeNonNegative = 6
    constraints = 7
    relation = 8
    formulaText = 9
End Enum
'
'
'
'
'
' Module : XLSFunctions
Option Explicit
'
Public Function GetSumOfSquaredDifferences(ByRef values As Excel.Range) As Double
    '
    Dim v As Variant: v = values.Value2
    Dim sumOfSquaredDifferences As Double
    Dim i As Integer
    '
    ' calculate sum of squared differences between all adjacent values
    For i = 1 To (UBound(v) - 1)
        sumOfSquaredDifferences = sumOfSquaredDifferences + ((v(i + 1, 1) - v(i, 1)) * (v(i + 1, 1) - v(i, 1)))
    Next i
    GetSumOfSquaredDifferences = sumOfSquaredDifferences
End Function
'
Public Function IRSwapLiborPV(ByRef forwards As Excel.Range, ByVal swapRate As Double, _
ByVal yearsToMaturity As Integer, ByVal floatingLegPaymentFrequency As Integer, ByVal notional As Double) As Double
    '
    ' PV (fixed payer swap) = -swapRate * Q(T) + (1 - DF(T))
    ' where Q(T) is sumproduct of fixed leg discount factors and corresponding time accrual factors
    ' assumption : fixed leg is always paid annually
    ' since fixed leg is paid annually and maturity is always integer, time accrual factor will always be exactly 1.0
    Dim f As Variant: f = forwards.Value2
    Dim DF As Double
    Dim Q As Double
    Dim floatingLegTenor As Double: floatingLegTenor = 1 / CDbl(floatingLegPaymentFrequency)
    Dim nextFixedLegCouponDate As Integer: nextFixedLegCouponDate = 1
    Dim currentTimePoint As Double: currentTimePoint = CDbl(0)
    '
    Dim i As Integer
    For i = 1 To (yearsToMaturity * floatingLegPaymentFrequency)
        '
        currentTimePoint = currentTimePoint + floatingLegTenor
        ' first rate is always spot rate, calculate first spot discount factor
        If (i = 1) Then
            DF = 1 / (1 + f(i, 1) * floatingLegTenor)
        End If
        '
        ' other rates are always forward rates
        If (i > 1) Then
            ' solve current spot discount factor using previous spot discount factor
            ' and current forward discount factor : DF(0,2) = DF(0,1) * DF(1,2)
            DF = DF * (1 / (1 + f(i, 1) * floatingLegTenor))
            If ((currentTimePoint - CDbl(nextFixedLegCouponDate)) = 0) Then
                Q = Q + DF
                nextFixedLegCouponDate = nextFixedLegCouponDate + 1
            End If
        End If
    Next i
    IRSwapLiborPV = (-swapRate * Q + (1 - DF)) * notional
End Function
'
'
'
'
'
' Class module : ISolver
Option Explicit
'
' ISolver interface to be implemented
Public Function solve(ByRef parameters As Scripting.Dictionary)
    ' no implementation
End Function
'
'
'
'
'
' Class module : ConstrainedOptimization
Option Explicit
'
Implements ISolver
'
' implementation for ISolver interface
' solver model for constrained optimization tasks
Private Function ISolver_solve(ByRef parameters As Scripting.Dictionary)
    '
    ' reset solver model
    solver.SolverReset
    '
    ' create optimization task
    solver.SolverOk _
        parameters.Item(PRM.objectiveFunction), _
        parameters.Item(PRM.maxMinVal), _
        parameters.Item(PRM.valueOf), _
        parameters.Item(PRM.changingVariables)
    '
    ' add constraints
    solver.SolverAdd _
        parameters(PRM.constraints), _
        parameters(PRM.relation), _
        parameters(PRM.formulaText)
    '
    ' solve optimization model
    solver.SolverOptions AssumeNonNeg:=parameters.Item(PRM.assumeNonNegative)
    solver.SolverSolve parameters.Item(PRM.userFinish)
End Function
'

Saturday, August 15, 2015

Bootstrapping Libor Discount Factor and Forward Rate Curves using C# and Excel-DNA

Defining a set of correct discount factors and forward rates is the cornerstone of valuing any Libor-based products. As we know, calculation of present value for a Libor cash flow seems to be almost too easy : first define a cash flow happening in the future by using forward rates, then use discount factors to get present value for that cash flow. Then we also know, that the real deal is always getting those forward rates and discount factors from somewhere, in the first place.

For the task described above, we usually have our front office system or tools provided by some third-party vendor, which are then performing all those required complex calculations quietly behind the scenes. Figures are popping up in the screen, finding their way into some strange reports and everyone are happy. Needless to say, we should be able to perform those calculations also by hand, if so required. This is only my personal opinion on the matter, of course. During this small project, we are creating a program, which takes in market data as input parameter. From this market data, the program is then performing all those complex calculations (bootstrapping, interpolations) and returning discount factors and simply-compounded Libor forward rates.

CURVOLOGY

When constructing discount factors and forward rates from market data, one has to make a lot of different decisions. Just for an example
  • How to construct short-end of the curve? For what maturities are we going to use cash securities?
  • How to construct mid-part of the curve? Are we using futures contracts on Libor or Forward Rate Agreements? 
  • Are we going to make adjustments for convexity effect?
  • How to construct long-end of the curve? For what maturity we start to use swap rates?
  • What kind of interpolation methods are we going to use?
  • Do we interpolate discount factors or spot rates?
Due to this high degrees of freedom embedded in this task, it should not be a miracle, that two persons (given the same set of market data) most probably will end up having completely different set of discount factors and forward rates. As I have been studying this topic and getting a bit more familiar with the methods and procedures used by some well-known authors, I have personally come to the conclusion that there are some common guidelines and general conventions, but absolutely not any one universally correct way to do this task.

MARKET DATA

For this project, I have been using dataset and curve creation procedures as presented in Richard Flavell's excellent book Swaps and Other Derivatives. In this book, Flavell is giving complete treatment, how to construct Libor zero curve (discount factors and forward rates). One of the things why I like so much this book is the fact, that Flavell is not assuming anything. Instead, he is always deriving everything from the beginning. Great thing is also, that the book has all the example calculations dissected in the attached Excel workbooks. Personally, these Excels have been sort of a goldmine for me, when I have been studying different valuation issues.

PROJECT OUTCOME

The result of this project is XLL addin for Excel, which calculates discount factors and simply-compounded forward rates for USD Libor. We will use Excel-DNA for interfacing our C# program with Excel. The scheme what has been used for this project, has been fully explained in this blog post. So, carefully follow the instructions given in that post, when interfacing the program with Excel. Needless to say, one should be able to use the core classes of the program (the classes which are actually creating the curves) in any other C# project, without Excel interfacing.

PROGRAM DESIGN

Rough UML class diagram for this program is shown below. The purpose of this diagram is to get some conceptual overview, how the program is working and how the objects are related with each other. Since I am not UML expert, I am presenting my deepest apologies for its incompleteness and possible errors.

In the first stage, Client (CreateUSDLiborCurves, which will be presented in the section Excel Interfacing) is requesting ExcelBuilder (specialization of abstract MarketDataBuilder) to build market data and return it as a CurveData object. Then, Client is creating and using USDLiborZeroCurve object (implementation of ICurve interface). Inside USDLiborZeroCurve object, the curves (discount factors and forward rates) are going to be created in different types of sequential calculations (data checking, data selection, bootstrapping, interpolation). Finally, Client is requesting ExcelPrinter (specialization of abstract CurvePrinter) object to print the resulting dataset into Excel worksheet. During the calculation process, USDLiborZeroCurve is also using two static classes (DateConvention and Interpolation, not shown in UML diagram), which contains different types of date-related and interpolation-related methods.


THE PROGRAM

The part of the program, which is creating the outcome curves (discount factors and forward rates), is shown below. Create a new Class project and just copyPaste everything into a new cs-file.


using System;
using System.Collections;
using System.Collections.Generic;
using System.Linq;
using ExcelDna.Integration;

namespace CurveAddin
{
    //
    // public enumerators and delegate methods
    public enum ENUM_MARKETDATATYPE { CASH = 1, FRA = 2, FUTURE = 3, SWAP = 4, DF = 5, SPOTRATE = 6, FORWARDRATE = 7 }
    public enum ENUM_PERIODTYPE { MONTHS = 1, YEARS = 2 }
    public delegate double DayCountFactor(DateTime start, DateTime end);
    public delegate DateTime AddPeriod(DateTime start, ENUM_PERIODTYPE periodType, int period);
    public delegate double Interpolator(DayCountFactor dayCountFactor, Dictionary<DateTime, double> data, DateTime key);
    public delegate double ConvexityAdjustment(double rateVolatility, double start, double end);
    //
    //
    // class hierarchy for curve printer
    public abstract class CurvePrinter
    {
        public abstract void Print();
    }
    public class ExcelPrinter : CurvePrinter
    {
        private static dynamic Excel;
        private dynamic[,] data;
        public ExcelPrinter(dynamic[,] data)
        {
            this.data = data;
        }
        public override void Print()
        {
            // Create Excel application
            Excel = ExcelDnaUtil.Application;
            //
            // clear old data from output range, resize output range 
            // and finally print data to Excel worksheet
            Excel.Range["_USDLiborZeroCurve"].CurrentRegion = "";
            Excel.Range["_USDLiborZeroCurve"].Resize[data.GetLength(0), data.GetLength(1)] = data;
        }
    }
    //
    //
    // class hierarchy for market data builder
    public abstract class MarketDataBuilder
    {
        public abstract CurveData Build();
    }
    public class ExcelBuilder : MarketDataBuilder
    {
        private static dynamic Excel;
        private DateTime settlementDate;
        public DateTime SettlementDate { get { return this.settlementDate; } }
        //
        public override CurveData Build()
        {
            // Create Excel application
            Excel = ExcelDnaUtil.Application;
            //
            // read settlement date from Excel worksheet
            settlementDate = DateTime.FromOADate((double)Excel.Range("_settlementDate").Value2);
            //
            // read source security data from Excel worksheet
            object[,] ExcelSourceData = (object[,])Excel.Range["_marketData"].CurrentRegion.Value2;
            //
            // create curve data object from source security data
            CurveData marketData = new CurveData(Interpolation.LinearInterpolation);
            int rows = ExcelSourceData.GetUpperBound(0);
            for (int i = 1; i <= rows; i++)
            {
                DateTime maturity = DateTime.FromOADate((double)ExcelSourceData[i, 1]);
                double rate = (double)ExcelSourceData[i, 2];
                string instrumentType = ((string)ExcelSourceData[i, 3]).ToUpper();
                ENUM_MARKETDATATYPE marketDataType = (ENUM_MARKETDATATYPE)Enum.Parse(typeof(ENUM_MARKETDATATYPE), instrumentType);
                marketData.AddCurveDataElement(maturity, rate, marketDataType);
            }
            return marketData;
        }
    }
    //
    //
    // interface for all curve objects
    public interface ICurve
    {
        void Create();
        double GetDF(DateTime maturity);
        double GetFWD(DateTime start);
        Dictionary<DateTime, double> GetDF(DateTime start, int nYears);
        Dictionary<DateTime, double> GetFWD(DateTime start, int nYears);
        CurveData DiscountCurve { get; }
        CurveData ForwardCurve { get; }
    }
    //
    // implementation for USD Libor curve
    public class USDLiborZeroCurve : ICurve
    {
        public readonly DayCountFactor dayCountFactor;
        public readonly AddPeriod addPeriod;
        public readonly int basis;
        public readonly Interpolator interpolator;
        public readonly DateTime settlementDate;
        public CurveData DiscountCurve { get { return this.discountCurve; } }
        public CurveData ForwardCurve { get { return this.forwardCurve; } }
        //
        private CurveData marketData;
        private CurveData curveDataSelection;
        private CurveData bootstrapCurve;
        private CurveData spotCurve;
        private CurveData discountCurve;
        private CurveData forwardCurve;
        private int nCash;
        private int nFuturesOrFRAs;
        private bool adjustmentForConvexity;
        private ConvexityAdjustment convexityAdjustment;
        private double rateVolatility;
        //
        public USDLiborZeroCurve(CurveData marketData, Interpolator interpolator, AddPeriod addPeriod,
            DayCountFactor dayCountFactor, DateTime settlementDate, int nCash, int nFuturesOrFRAs,
            bool adjustmentForConvexity = false, ConvexityAdjustment convexityAdjustment = null, double rateVolatility = 0.0)
        {
            this.marketData = marketData;
            this.interpolator = interpolator;
            this.addPeriod = addPeriod;
            this.dayCountFactor = dayCountFactor;
            this.settlementDate = settlementDate;
            this.nCash = nCash;
            this.nFuturesOrFRAs = nFuturesOrFRAs;
            this.basis = 3; // HARD-CODED !! for USD Libor curve
            this.adjustmentForConvexity = adjustmentForConvexity; // optional parameter
            this.convexityAdjustment = convexityAdjustment; // optional parameter
            this.rateVolatility = rateVolatility; // optional parameter
        }
        public void Create()
        {
            // sequence of private methods for creating spot discount curve and
            // simply-compounded forward rate curve for a given set of market data
            checkMarketData();
            selectCurveData();
            bootstrapDiscountFactors();
            createSpotCurve();
            createDiscountCurve();
            createForwardCurve();
        }
        // get discount factor for a given maturity date
        public double GetDF(DateTime maturity)
        {
            return discountCurve.GetMarketRate(ENUM_MARKETDATATYPE.DF, maturity, dayCountFactor);
        }
        // get dictionary consisting of date and discount factor for a date schedule
        public Dictionary<DateTime, double> GetDF(DateTime start, int nYears)
        {
            List<DateTime> schedule = DateConvention.CreateDateSchedule(start, nYears, basis, ENUM_PERIODTYPE.MONTHS, addPeriod);
            Dictionary<DateTime, double> curve = new Dictionary<DateTime, double>();
            schedule.ForEach(it => curve.Add(it, GetDF(it)));
            return curve;
        }
        // get simply-compounded forward rate for a given start date
        public double GetFWD(DateTime start)
        {
            return forwardCurve.GetMarketRate(ENUM_MARKETDATATYPE.FORWARDRATE, start, dayCountFactor);
        }
        // get dictionary consisting of date and simply-compounded forward rate for a date schedule
        public Dictionary<DateTime, double> GetFWD(DateTime start, int nYears)
        {
            List<DateTime> schedule = DateConvention.CreateDateSchedule(start, nYears, basis, ENUM_PERIODTYPE.MONTHS, addPeriod);
            Dictionary<DateTime, double> curve = new Dictionary<DateTime, double>();
            schedule.ForEach(it => curve.Add(it, GetFWD(it)));
            return curve;
        }
        // use interpolated spot discount factor curve for calculating
        // simply-compounded forward rates for all required maturities (basis)
        // note : maturity element of the forward curve stores the information
        // on when the 3-month period starts for a given forward rate element
        private void createForwardCurve()
        {
            forwardCurve = new CurveData(interpolator);
            int n = discountCurve.Count();
            DateTime maturity;
            double dt = 0.0;
            double fdf = 0.0;
            double f = 0.0;
            //
            for (int i = 0; i < n; i++)
            {
                if (i == 0)
                {
                    // first forward rate is the first spot rate
                    maturity = discountCurve[i].MaturityDate;
                    fdf = discountCurve[i].Rate;
                    dt = dayCountFactor(settlementDate, maturity);
                    f = ((1 / fdf) - 1) / dt;
                    forwardCurve.AddCurveDataElement(settlementDate, f, ENUM_MARKETDATATYPE.FORWARDRATE);
                }
                else
                {
                    // other forward rates are calculated recursively
                    // from previous spot discount factors
                    maturity = discountCurve[i].MaturityDate;
                    DateTime previousMaturity = discountCurve[i - 1].MaturityDate;
                    fdf = discountCurve[i].Rate / discountCurve[i - 1].Rate;
                    dt = dayCountFactor(previousMaturity, maturity);
                    f = ((1 / fdf) - 1) / dt;
                    forwardCurve.AddCurveDataElement(previousMaturity, f, ENUM_MARKETDATATYPE.FORWARDRATE);
                }
            }
        }
        // use continuously compounded spot rate curve for interpolating 
        // continuously compounded spot rates for all required maturities 
        // and convert these spot rates back to spot discount factors
        private void createDiscountCurve()
        {
            discountCurve = new CurveData(interpolator);
            DateTime finalCurveDate = spotCurve.ElementAt(spotCurve.Count() - 1).MaturityDate;
            DateTime t;
            int counter = 0;
            double dt = 0.0;
            double r = 0.0;
            double df = 0.0;
            //
            do
            {
                counter++;
                t = addPeriod(settlementDate, ENUM_PERIODTYPE.MONTHS, basis * counter);
                dt = dayCountFactor(settlementDate, t);
                r = spotCurve.GetMarketRate(ENUM_MARKETDATATYPE.SPOTRATE, t, dayCountFactor);
                df = Math.Exp(-r * dt);
                discountCurve.AddCurveDataElement(t, df, ENUM_MARKETDATATYPE.DF);
            } while (t < finalCurveDate);
        }
        // create continuously compounded spot rate curve 
        // from bootstrapped discount factors
        private void createSpotCurve()
        {
            spotCurve = new CurveData(interpolator);
            double t = 0.0;
            double r = 0.0;
            int n = bootstrapCurve.Count();
            for (int i = 0; i < n; i++)
            {
                t = dayCountFactor(settlementDate, bootstrapCurve.ElementAt(i).MaturityDate);
                r = -Math.Log(bootstrapCurve.ElementAt(i).Rate) / t;
                spotCurve.AddCurveDataElement(bootstrapCurve.ElementAt(i).MaturityDate, r, ENUM_MARKETDATATYPE.SPOTRATE);
            }
        }
        // use bootstrap algorithm to create spot discount factors
        // from all selected curve data elements
        private void bootstrapDiscountFactors()
        {
            bootstrapCurve = new CurveData(interpolator);
            double dt = 0.0;
            double r = 0.0;
            double df = 0.0;
            double Q = 0.0;
            int n = curveDataSelection.Count();
            //
            for (int i = 0; i < n; i++)
            {
                if (curveDataSelection[i].InstrumentType == ENUM_MARKETDATATYPE.CASH)
                {
                    dt = dayCountFactor(settlementDate, curveDataSelection[i].MaturityDate);
                    r = curveDataSelection[i].Rate;
                    df = 1 / (1 + r * dt);
                    bootstrapCurve.AddCurveDataElement(curveDataSelection[i].MaturityDate, df, ENUM_MARKETDATATYPE.DF);
                }
                if ((curveDataSelection[i].InstrumentType == ENUM_MARKETDATATYPE.FRA) |
                    (curveDataSelection[i].InstrumentType == ENUM_MARKETDATATYPE.FUTURE))
                {
                    dt = dayCountFactor(curveDataSelection[i - 1].MaturityDate, curveDataSelection[i].MaturityDate);
                    r = curveDataSelection[i].Rate;
                    df = bootstrapCurve.ElementAt(i - 1).Rate / (1 + r * dt);
                    bootstrapCurve.AddCurveDataElement(curveDataSelection[i].MaturityDate, df, ENUM_MARKETDATATYPE.DF);
                    //
                    if ((curveDataSelection[i + 1].InstrumentType == ENUM_MARKETDATATYPE.SWAP))
                        Q += bootstrapCurve.ElementAt(i).Rate * dayCountFactor(settlementDate, curveDataSelection[i].MaturityDate);
                }
                //
                if (curveDataSelection[i].InstrumentType == ENUM_MARKETDATATYPE.SWAP)
                {
                    r = curveDataSelection[i].Rate;
                    dt = dayCountFactor(bootstrapCurve.ElementAt(i - 1).MaturityDate, curveDataSelection[i].MaturityDate);
                    df = (1 - r * Q) / (r * dt + 1);
                    bootstrapCurve.AddCurveDataElement(curveDataSelection[i].MaturityDate, df, ENUM_MARKETDATATYPE.DF);
                    Q += (df * dt);
                }
            }
        }
        // select rate instruments to be used from a given set of curve data elements
        private void selectCurveData()
        {
            curveDataSelection = new CurveData(interpolator);
            int counter = 0;
            double rate = 0.0;
            DateTime maturityDate;
            //
            // select cash securities
            for (int i = 1; i <= nCash; i++)
            {
                counter++;
                maturityDate = addPeriod(settlementDate, ENUM_PERIODTYPE.MONTHS, basis * counter);
                // check if cash rate for required maturity exists
                if (!marketData.ElementLookup(ENUM_MARKETDATATYPE.CASH, maturityDate))
                    throw new Exception("USDLiborZeroCurve error : required cash securities are missing");
                rate = marketData.GetMarketRate(ENUM_MARKETDATATYPE.CASH, maturityDate, dayCountFactor);
                curveDataSelection.AddCurveDataElement(maturityDate, rate, ENUM_MARKETDATATYPE.CASH);
            }
            // select fra or futures contracts
            if (marketData.ElementLookup(ENUM_MARKETDATATYPE.FRA))
            {
                for (int i = 1; i <= nFuturesOrFRAs; i++)
                {
                    if (i > 1) counter++;
                    maturityDate = addPeriod(settlementDate, ENUM_PERIODTYPE.MONTHS, basis * counter);
                    // check if fra rate for required maturity exists
                    if (!marketData.ElementLookup(ENUM_MARKETDATATYPE.FRA, maturityDate))
                        throw new Exception("USDLiborZeroCurve error : required FRA contracts are missing");
                    rate = marketData.GetMarketRate(ENUM_MARKETDATATYPE.FRA, maturityDate, dayCountFactor);
                    curveDataSelection.AddCurveDataElement(addPeriod(maturityDate, ENUM_PERIODTYPE.MONTHS, basis), rate, ENUM_MARKETDATATYPE.FRA);
                }
            }
            else
            {
                for (int i = 1; i <= nFuturesOrFRAs; i++)
                {
                    if (i > 1) counter++;
                    maturityDate = addPeriod(settlementDate, ENUM_PERIODTYPE.MONTHS, basis * counter);
                    // check if implied futures rate for required maturity exists
                    if (!marketData.ElementLookup(ENUM_MARKETDATATYPE.FUTURE, maturityDate))
                        throw new Exception("USDLiborZeroCurve error : required futures contracts are missing");
                    rate = marketData.GetMarketRate(ENUM_MARKETDATATYPE.FUTURE, maturityDate, dayCountFactor);
                    //
                    // forward rate = futures rate - convexity adjustment
                    if (adjustmentForConvexity)
                    {
                        double t1 = dayCountFactor(settlementDate, maturityDate);
                        double t2 = t1 + (basis / 12.0);
                        rate -= convexityAdjustment(rateVolatility, t1, t2);
                    }
                    curveDataSelection.AddCurveDataElement(addPeriod(maturityDate, ENUM_PERIODTYPE.MONTHS, basis), rate, ENUM_MARKETDATATYPE.FUTURE);
                }
            }
            // select swap contracts
            DateTime lastSwapYear = marketData[marketData.Count() - 1].MaturityDate;
            DateTime lastFRAOrFutureYear = curveDataSelection[curveDataSelection.Count() - 1].MaturityDate;
            int nSwaps = (lastSwapYear.Year - lastFRAOrFutureYear.Year);
            for (int i = 1; i <= nSwaps; i++)
            {
                counter++;
                maturityDate = addPeriod(settlementDate, ENUM_PERIODTYPE.YEARS, i + 1);
                // check if swap rate for required maturity exists
                if (!marketData.ElementLookup(ENUM_MARKETDATATYPE.SWAP, maturityDate))
                    throw new Exception("USDLiborZeroCurve error : required swap contracts are missing");
                rate = marketData.GetMarketRate(ENUM_MARKETDATATYPE.SWAP, maturityDate, dayCountFactor);
                curveDataSelection.AddCurveDataElement(maturityDate, rate, ENUM_MARKETDATATYPE.SWAP);
            }
        }
        // rough diagnostics : check for completely non-existing market data
        // requirement : all three rate categories (cash, FRA/futures, swaps) 
        // must be provided by the client in order to create the curves
        private void checkMarketData()
        {
            // cash securities
            if (!marketData.ElementLookup(ENUM_MARKETDATATYPE.CASH))
                throw new Exception("LiborZeroCurve error : cash securities are required to build the curve");
            //
            // fra/futures contracts
            if ((!marketData.ElementLookup(ENUM_MARKETDATATYPE.FUTURE)) && (!marketData.ElementLookup(ENUM_MARKETDATATYPE.FRA)))
                throw new Exception("LiborZeroCurve error : FRA or futures contracts are required to build the curve");
            //
            // swap contracts
            if (!marketData.ElementLookup(ENUM_MARKETDATATYPE.SWAP))
                throw new Exception("LiborZeroCurve error : swap contracts are required to build the curve");
        }
    }
    //
    //
    // container class for holding multiple curve data elements
    public class CurveData : IEnumerable<CurveDataElement>
    {
        private List<CurveDataElement> curveDataElements;
        private Interpolator interpolator;
        //
        public CurveData(Interpolator interpolator)
        {
            this.interpolator = interpolator;
            curveDataElements = new List<CurveDataElement>();
        }
        public void AddCurveDataElement(DateTime maturity, double rate, ENUM_MARKETDATATYPE instrumentType)
        {
            curveDataElements.Add(new CurveDataElement(maturity, rate, instrumentType));
        }
        public void AddCurveDataElement(CurveDataElement curveDataElement)
        {
            curveDataElements.Add(curveDataElement);
        }
        // implementation for generic IEnumerable
        public IEnumerator<CurveDataElement> GetEnumerator()
        {
            foreach (CurveDataElement curveDataElement in curveDataElements)
            {
                yield return curveDataElement;
            }
        }
        // implementation for non-generic IEnumerable
        IEnumerator IEnumerable.GetEnumerator()
        {
            return GetEnumerator();
        }
        // read-only indexer
        public CurveDataElement this[int index]
        {
            get
            {
                return curveDataElements[index];
            }
        }
        public double GetMarketRate(ENUM_MARKETDATATYPE instrumentType, DateTime maturity, DayCountFactor dayCountFactor)
        {
            // filter required market data elements by instrument type
            List<CurveDataElement> group = curveDataElements.Where(it => it.InstrumentType == instrumentType).ToList<CurveDataElement>();
            //
            // extract maturity and rate into dictionary object
            Dictionary<DateTime, double> data = new Dictionary<DateTime, double>();
            group.ForEach(it => data.Add(it.MaturityDate, it.Rate));
            //
            // get market rate for a given date by using given interpolation delegate method
            return interpolator(dayCountFactor, data, maturity);
        }
        // check if elements with specific instrument type and maturity exists
        public bool ElementLookup(ENUM_MARKETDATATYPE instrumentType, DateTime maturity)
        {
            // first, filter required market data elements
            List<CurveDataElement> group = curveDataElements.Where(it => it.InstrumentType == instrumentType).ToList<CurveDataElement>();
            //
            // then, check if maturity lies between min and max maturity of filtered group
            bool hasElement = ((maturity >= group.Min(it => it.MaturityDate)) && (maturity <= group.Max(it => it.MaturityDate)));
            return hasElement;
        }
        // check if elements with only specific instrument type exists
        public bool ElementLookup(ENUM_MARKETDATATYPE instrumentType)
        {
            int elements = curveDataElements.Count(it => it.InstrumentType == instrumentType);
            bool hasElements = false;
            if (elements > 0) hasElements = true;
            return hasElements;
        }
    }
    //
    //
    // class holding information on one curve data element
    public class CurveDataElement
    {
        private DateTime maturityDate;
        private double rate;
        private ENUM_MARKETDATATYPE rateType;
        //
        public DateTime MaturityDate { get { return this.maturityDate; } }
        public double Rate { get { return this.rate; } }
        public ENUM_MARKETDATATYPE InstrumentType { get { return this.rateType; } }
        //
        public CurveDataElement(DateTime maturity, double rate, ENUM_MARKETDATATYPE rateType)
        {
            this.maturityDate = maturity;
            this.rate = rate;
            this.rateType = rateType;
        }
    }
    //
    //
    // static library class for handling date-related convention calculations
    public static class DateConvention
    {
        // calculate time difference between two dates by using ACT/360 convention
        public static double ACT360(DateTime start, DateTime end)
        {
            return (end - start).TotalDays / 360;
        }
        // create a list of scheduled dates for a given basis and date convention
        public static List<DateTime> CreateDateSchedule(DateTime start, int nYears, int basis,
            ENUM_PERIODTYPE periodType, AddPeriod addPeriod)
        {
            List<DateTime> schedule = new List<DateTime>();
            int nPeriods = nYears * (12 / basis);
            for (int i = 1; i <= nPeriods; i++)
            {
                schedule.Add(addPeriod(start, periodType, (basis * i)));
            }
            return schedule;
        }
        // add period into a given date by using modified following convention
        public static DateTime AddPeriod_ModifiedFollowing(DateTime start, ENUM_PERIODTYPE periodType, int period)
        {
            DateTime dt = new DateTime();
            //
            switch (periodType)
            {
                case ENUM_PERIODTYPE.MONTHS:
                    dt = start.AddMonths(period);
                    break;
                case ENUM_PERIODTYPE.YEARS:
                    dt = start.AddYears(period);
                    break;
            }
            //
            switch (dt.DayOfWeek)
            {
                case DayOfWeek.Saturday:
                    dt = dt.AddDays(2.0);
                    break;
                case DayOfWeek.Sunday:
                    dt = dt.AddDays(1.0);
                    break;
            }
            return dt;
        }
        // calculate value for convexity adjustment for a given time period
        public static double SimpleConvexityApproximation(double rateVolatility, double start, double end)
        {
            return 0.5 * (rateVolatility * rateVolatility * start * end);
        }
    }
    //
    //
    // static library class for storing interpolation methods to be used by delegates
    public static class Interpolation
    {
        public static double LinearInterpolation(DayCountFactor dayCountFactor,
            Dictionary<DateTime, double> data, DateTime key)
        {
            double value = 0.0;
            int n = data.Count;
            //
            // boundary checkings
            if ((key < data.ElementAt(0).Key) || (key > data.ElementAt(data.Count - 1).Key))
            {
                if (key < data.ElementAt(0).Key) throw new Exception("Interpolation error : lower bound violation");
                if (key > data.ElementAt(data.Count - 1).Key) throw new Exception("Interpolation error : upper bound violation");
            }
            else
            {
                // iteration through all existing elements
                for (int i = 0; i < n; i++)
                {
                    if ((key >= data.ElementAt(i).Key) && (key <= data.ElementAt(i + 1).Key))
                    {
                        double t = dayCountFactor(data.ElementAt(i).Key, data.ElementAt(i + 1).Key);
                        double w = dayCountFactor(data.ElementAt(i).Key, key) / t;
                        value = data.ElementAt(i).Value * (1 - w) + data.ElementAt(i + 1).Value * w;
                        break;
                    }
                }
            }
            return value;
        }
    }
}


EXCEL INTERFACING

For interfacing the previous C# program with Excel, carefully follow all the instructions given in this blog post. Add another Class module (a new cs-file) into this project and copyPaste the following program into this file. This is the program (CreateUSDLiborCurves), which will be called from our Excel worksheet.


using System;
using System.Collections.Generic;
using System.Linq;
using System.Text;
using System.Windows.Forms;
using ExcelDna.Integration;

namespace CurveAddin
{
    public static class CurveAddin
    {
        public static void CreateUSDLiborCurves()
        {
            try
            {
                // build market data from Excel worksheet
                MarketDataBuilder builder = new ExcelBuilder();
                CurveData marketData = builder.Build();
                DateTime settlementDate = ((ExcelBuilder)builder).SettlementDate;
                //
                // construct USD Libor curve object
                // HARD-CODED parameters : 
                // interpolation method, date conventions, number of contracts for cash (n=1) and futures (n=3)
                ICurve curve = new USDLiborZeroCurve(marketData, Interpolation.LinearInterpolation, 
                    DateConvention.AddPeriod_ModifiedFollowing, DateConvention.ACT360, settlementDate, 1, 3);
                curve.Create();
                //
                // read discount factor and forward rate data into 2d-array
                int rows = curve.DiscountCurve.Count();
                int cols = 3;
                dynamic[,] data = new dynamic[rows, cols];
                for (int i = 0; i < rows; i++)
                {
                    data[i, 0] = curve.DiscountCurve[i].MaturityDate.ToOADate();
                    data[i, 1] = curve.DiscountCurve[i].Rate;
                    data[i, 2] = curve.ForwardCurve[i].Rate;
                }
                //
                // print curve data into Excel worksheet
                (new ExcelPrinter(data)).Print();
            }
            catch (Exception e)
            {
                MessageBox.Show(e.Message);
            }
        }
    }
}


EXCEL WORKSHEET SETTINGS

Prepare the following market data (Flavell's book and Excel workbook on chapter three) and named ranges (marked with yellow color) into Excel worksheet. The program will take settlement date and market data range (date, rate, rate type) as input parameters. Note, that some of the parameters needed to create the curves have been hard-coded in the program (interpolation method, date conventions, number of contracts for cash and futures). However, it should be fairly straightforward to include all these parameters to be read directly from Excel worksheet. Finally, insert a form control button into worksheet and assign a macro for it (CreateUSDLiborCurves).


Finally, a couple of notes concerning the market data setting. When creating Curve object, Client has to provide number of cash securities and number futures/FRA contracts as input parameters in constructor. Example program has been hard-coded to use one cash security and three futures contracts and it will hereby use Libor swap contracts starting on the year two. Now, for setting market data for this program, there are some general rules. First, the latest maturity for cash securities has to be later than the first maturity for futures/FRA contracts. Also, the last future/FRA maturity has to be later than the first swap contract maturity date minus one year.

TEST RUN

After I press button in my Excel, I will get the following results (columns H to J) from the program. The range consists of dates (quarterly up to 8.2.2038), discount factors and simply-compounded Libor forward rates for USD. The first result row should be interpreted as follows : discount factor (0.99220) gives factor for discounting three-month cash flow. Simply-compounded Libor forward rate (3.1450 %) gives three-month forward rate for a period, which is starting on 6.2.2008 and ending 6.5.2008. Similarly, Libor forward rate (2.7837 %) gives three-month forward rate for a period, which is starting on 6.5.2008 and ending 6.8.2008.


After this, using generated curves (discount factors and forward rates) is straightforward. As an example, I have calculated PV for 2-year cap on 3-month USD Libor. After creating date schedule for this security, getting forward rates and discount factors can be requested by using familiar Excel worksheet functions.


AFTERTHOUGHTS

The procedure of creating discount factors and Libor forward rates programmatically in C#, has been fully opened in this blog post. Source market data and creation procedures are following examples taken from the book written by Richard Flavell. With the tools presented in this blog, one should also be able to interface this program with Excel, if so desired.

I would like to thank Govert Van Drimmelen again for his amazing Excel-DNA, what I am always using for interfacing my C# program with Excel. For learning more things about Excel-DNA, check out its homepage. Getting more information and examples with your problems, the main source is Excel-DNA google group. Remember also, that Excel-DNA is an open-source project, and we (the happy users) can invest its future development by making a donation.

Finally, Thanks for spending your precious time in here and reading my blog.

-Mike Juniperhill