Wednesday, April 27, 2016

QuantLib : Least squares method implementation

A couple of years ago I published a blog post on using Microsoft Solver Foundation for curve fitting. In this post we go through that example again, but this time using corresponding Quantlib (QL) tools. In order to make everything a bit more concrete, the fitting scheme (as solved by Frontline Solver in Microsoft Excel) is presented in the screenshot below.


Second degree polynomial fitting has been performed, in order to find a set of coefficients which are minimizing sum of squared differences between observed rates and estimated rates. The same minimization scheme has also been used in my example program presented later below.


LeastSquares class


After some initial woodshedding with QL optimization tools, I started to dream if it could be possible to create kind of a generic class, which could then handle all kinds of different curve fitting schemes.

When using LeastSquares class, client is creating its instance by setting desired optimization method (Quantlib::OptimizationMethod) and all parameters needed for defining desired end criteria (Quantlib::EndCriteria) for optimization procedure. The actual fitting procedure will be started by calling Fit method of LeastSquares class. For this method, client is giving independent values (Quantlib::Array), vector of function pointers (boost::function), initial parameters (Quantlib::Array) and parameter constraints (Quantlib::Constraint).

Objective function implementation (Quantlib::CostFunction) used by QL optimizers is hidden as a nested class inside LeastSquares class. Since the actual task performed by least squares method is always to minimize a sum of squared errors, this class is not expected to change. Objective function is then using a set of given independent values and function pointers (boost::function) to calculate sum of squared errors between independent (observed) values and estimated values. By using function pointers (boost::function), algorithm will not be hard-coded into class method.

Finally, for function pointers used in objective function inside LeastSquares class, implementation class with correct method signature is expected to be available. In the example program, there is CurvePoint class, which is modelling a rate approximation for a given t (maturity) and a set of given external parameters.


Example program


Create a new C++ console project and copyPaste the following into corresponding header and implementation files. Help is available here if needed. In documentations page, there are three excellent presentation slides on Boost and Quantlib libraries by Dimitri Reiswich. "Hello world" examples of QuantLib optimizers can be found within these files.

Finally, thanks again for reading my blog.
-Mike


// CurvePoint.h
#pragma once
#include <ql/quantlib.hpp>
using namespace QuantLib;
//
// class modeling rate approximation for a single 
// curve point using a set of given parameters
class CurvePoint
{
private:
 Real t;
public:
 CurvePoint(Real t);
 Real operator()(const Array& coefficients);
};
//
//
//
// CurvePoint.cpp
#include "CurvePoint.h"
//
CurvePoint::CurvePoint(Real t) : t(t) { }
Real CurvePoint::operator()(const Array& coefficients)
{
 Real approximation = 0.0;
 for (unsigned int i = 0; i < coefficients.size(); i++)
 {
  approximation += coefficients[i] * pow(t, i);
 }
 return approximation;
}
//
//
//
// LeastSquares.h
#pragma once
#include <ql/quantlib.hpp>
using namespace QuantLib;
//
class LeastSquares
{
public:
 LeastSquares(boost::shared_ptr<OptimizationMethod> solver, Size maxIterations, Size maxStationaryStateIterations, 
  Real rootEpsilon, Real functionEpsilon, Real gradientNormEpsilon);
 //
 Array Fit(const Array& independentValues, std::vector<boost::function<Real(const Array&)>> dependentFunctions, 
  const Array& initialParameters, Constraint parametersConstraint);
private:
 boost::shared_ptr<OptimizationMethod> solver;
 Size maxIterations; 
 Size maxStationaryStateIterations;
 Real rootEpsilon; 
 Real functionEpsilon;
 Real gradientNormEpsilon;
 //
 // cost function implementation as private nested class 
 class ObjectiveFunction : public CostFunction
 {
 private:
  std::vector<boost::function<Real(const Array&)>> dependentFunctions;
  Array independentValues;
 public:
  ObjectiveFunction(std::vector<boost::function<Real(const Array&)>> dependentFunctions, const Array& independentValues);
  Real value(const Array& x) const;
  Disposable<Array> values(const Array& x) const;
 };
};
//
//
//
// LeastSquares.cpp
#pragma once
#include "LeastSquares.h"
//
LeastSquares::LeastSquares(boost::shared_ptr<OptimizationMethod> solver, Size maxIterations, 
 Size maxStationaryStateIterations, Real rootEpsilon, Real functionEpsilon, Real gradientNormEpsilon)
 : solver(solver), maxIterations(maxIterations), maxStationaryStateIterations(maxStationaryStateIterations),
 rootEpsilon(rootEpsilon), functionEpsilon(functionEpsilon), gradientNormEpsilon(gradientNormEpsilon) { }
//
Array LeastSquares::Fit(const Array& independentValues, std::vector<boost::function<Real(const Array&)>> dependentFunctions, 
 const Array& initialParameters, Constraint parametersConstraint)
{
 ObjectiveFunction objectiveFunction(dependentFunctions, independentValues);
 EndCriteria endCriteria(maxIterations, maxStationaryStateIterations, rootEpsilon, functionEpsilon, gradientNormEpsilon);
 Problem optimizationProblem(objectiveFunction, parametersConstraint, initialParameters);
 //LevenbergMarquardt solver;
 EndCriteria::Type solution = solver->minimize(optimizationProblem, endCriteria);
 return optimizationProblem.currentValue();
}
LeastSquares::ObjectiveFunction::ObjectiveFunction(std::vector<boost::function<Real(const Array&)>> dependentFunctions, 
 const Array& independentValues) : dependentFunctions(dependentFunctions), independentValues(independentValues) { }
//
Real LeastSquares::ObjectiveFunction::value(const Array& x) const
{
 // calculate squared sum of differences between
 // observed and estimated values
 Array differences = values(x);
 Real sumOfSquaredDifferences = 0.0;
 for (unsigned int i = 0; i < differences.size(); i++)
 {
  sumOfSquaredDifferences += differences[i] * differences[i];
 }
 return sumOfSquaredDifferences;
}
Disposable<Array> LeastSquares::ObjectiveFunction::values(const Array& x) const
{
 // calculate differences between all observed and estimated values using 
 // function pointers to calculate estimated value using a set of given parameters
 Array differences(dependentFunctions.size());
 for (unsigned int i = 0; i < dependentFunctions.size(); i++)
 {
  differences[i] = dependentFunctions[i](x) - independentValues[i];
 }
 return differences;
}
//
//
//
// tester.cpp
#include "LeastSquares.h"
#include "CurvePoint.h"
//
int main()
{
 // 2nd degree polynomial least squares fitting for a curve
 // create observed market rates for a curve
 Array independentValues(9);
 independentValues[0] = 0.19; independentValues[1] = 0.27; independentValues[2] = 0.29; 
 independentValues[3] = 0.35; independentValues[4] = 0.51; independentValues[5] = 1.38; 
 independentValues[6] = 2.46; independentValues[7] = 3.17; independentValues[8] = 3.32;
 //
 // create corresponding curve points to be approximated
 std::vector<boost::shared_ptr<CurvePoint>> curvePoints;
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(0.083)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(0.25)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(0.5)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(1.0)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(2.0)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(5.0)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(10.0)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(20.0)));
 curvePoints.push_back(boost::shared_ptr<CurvePoint>(new CurvePoint(30.0)));
 //
 // create container for function pointers for calculating rate approximations
 std::vector<boost::function<Real(const Array&)>> dependentFunctions;
 //
 // for each curve point object, bind function pointer to operator() and add it into container
 for (unsigned int i = 0; i < curvePoints.size(); i++)
 {
  dependentFunctions.push_back(boost::bind(&CurvePoint::operator(), curvePoints[i], _1));
 }
 // perform least squares fitting and print optimized coefficients
 LeastSquares leastSquares(boost::shared_ptr<OptimizationMethod>(new LevenbergMarquardt), 10000, 1000, 1E-09, 1E-09, 1E-09);
 NoConstraint parametersConstraint;
 Array initialParameters(3, 0.0);
 Array coefficients = leastSquares.Fit(independentValues, dependentFunctions, initialParameters, parametersConstraint);
 for (unsigned int i = 0; i < coefficients.size(); i++)
 {
  std::cout << coefficients[i] << std::endl;
 }
 return 0;
}

Sunday, April 10, 2016

C# : flexible design for processing market data

Third-party analytics softwares will usually require a full set of market data to be feeded into system, before performing any of those precious high intensity calculations. Market data (curves, surfaces, fixing time-series, etc.) has to be feeded into system following some specific file configurations. Moreover, source data might have to be collected from several different vendor sources. Needless to say, the process can easily turn into a semi-manageable mess involving Excel workbooks and a lot of manual processing, which is always a bad omen.

For this reason, I finally ended up creating one possible design solution for flexible processing of market data files. I have been going through some iterations starting with Abstract Factory, before landing with the current one using Delegates to pair data and algorithms. With the current solution, I start to feel quite comfortable already.


UML


Each market data point (such as mid USD swap rate for 2 years) is presented as a RiskFactor object. All individual RiskFactor objects are hosted in a list inside generic MarketDataElements<T> object, which enables hosting any type of data. MarketDataElements<T> object itself is hosted by static BaseMarket class.

The actual algorithms needed for creating any type of vendor data are captured in static ProcessorLibrary class. During the processing task, MarketDataElements<T> object will be handled for a specific library method implementation, which will then request values from vendor source for all involved RiskFactor objects. In the example program, ProcessorLibrary has a method for processing RiskFactor objects using Bloomberg market data API. This specific method is then using DummyBBCOMMWrapper class for requesting values for a RiskFactor object.

For the purpose of pairing specific data (MarketDataElements<T>) and specific algorithm (ProcessorLibrary), BaseMarket class is hosting a list of ElementProcessor objects as well as a list of Delegates bound with specific methods found in ProcessorLibrary. For the processing task, each ElementProcessor object is feeded with delegate method for specific ProcessorLibrary implementation method and information on MarketDataElements<T> object.

Finally, (not shown in UML) program is also using static TextFileHandler class for handling text files and static Configurations class for hosting hardcoded configurations, initially read from App.config file.


Files


App.config


CSV for all RiskFactor object configurations
Fields (matching with RiskFactor object properties) :
  • Data vendor identification string, matching with the one given in configuration file
  • Identification code (ticker) for a market data element, found in the system for which the data will be created
  • Vendor ticker for a market data element (Bloomberg ISIN code)
  • Field name for a market data element (Bloomberg field PX_MID)
  • Divider (Bloomberg is presenting a rate as percentage 1.234, but target system may need to have an input as absolute value 0.01234)
  • Empty field for a value to be processed by specific processor implementation for specific data vendor. 
 

Result CSV


The program


Create a new console project and CopyPaste the following program into corresponding CS files. When testing the program in a real production environment, just add reference to Bloomberg API DLL file and replace DummyBBCOMMWrapper class with this.

Adding a new data vendor processor XYZ involves the following four easy steps :
  1. Update providers in App.config file : <add key="RiskFactorDataProviders" value="BLOOMBERG,XYZ" />
  2. Create a new method implementation into ProcessorLibrary :  public static void ProcessXYZRiskFactors(dynamic marketDataElements) { // implement algorithm}
  3. Add selection for a new processor into BaseMarket class method createElementProcessors: if(dataProviderString.ToUpper() == "XYZ") elementProcessors.Add(new ElementProcessor(ProcessorLibrary.ProcessXYZRiskFactors, elements));
  4. Create new RiskFactor object configurations into source file for a new vendor XYZ
Finally, thanks for reading my blog.
-Mike


// MainProgram.cs
using System;
using System.Collections.Generic;
using System.Linq;
using System.Text;

namespace MarketDataProcess
{
    class MainProgram
    {
        static void Main(string[] args)
        {
            try
            {
                // process base market risk factors to file
                BaseMarket.Process();
                BaseMarket.PrintToFile();
            }
            catch (Exception e)
            {
                Console.WriteLine(e.Message);
            }
        }
    }
}
//
//
//
//
// BaseMarket.cs
using System;
using System.Collections.Generic;
using System.Linq;
using System.Text;

namespace MarketDataProcess
{
    // class for administrating risk factors and processors for base market
    public static class BaseMarket
    {
        private static List<string> inputFileStreams = new List<string>();
        private static MarketDataElements<RiskFactor> riskFactors = new MarketDataElements<RiskFactor>();
        private static List<ElementProcessor> elementProcessors = new List<ElementProcessor>();
        private static int nRiskFactors = 0;
        //
        public static void Process()
        {
            // read all source data string streams from file into list
            TextFileHandler.Read(Configurations.BaseMarketSourceDataFilePathName, inputFileStreams);
            //
            // extract string streams and create risk factor objects
            foreach (string inputFileStream in inputFileStreams)
            {
                RiskFactor element = new RiskFactor();
                element.Create(inputFileStream);
                riskFactors.AddElement(element);
            }
            nRiskFactors = riskFactors.elements.Count;
            //
            // create and execute market data element processors
            // finally run technical check on created risk factors
            BaseMarket.createElementProcessors();
            elementProcessors.ForEach(processor => processor.Process());
            BaseMarket.Check();
        }
        public static void PrintToFile()
        {
            // write created base market risk factors into file
            StringBuilder stream = new StringBuilder();
            for (int i = 0; i < riskFactors.elements.Count; i++)
            {
                stream.AppendLine(String.Format("{0},{1}", riskFactors.elements[i].systemTicker, riskFactors.elements[i].value));
            }
            TextFileHandler.Write(Configurations.BaseMarketResultDataFilePathName, stream.ToString(), false);
        }
        private static void createElementProcessors()
        {
            // market data element processor types are defined in configuration file
            List<string> dataProviderStrings = Configurations.RiskFactorDataProviders.Split(',').ToList<string>();
            //
            foreach (string dataProviderString in dataProviderStrings)
            {
                if (dataProviderString == String.Empty) throw new Exception("No element processor defined");
                List<RiskFactor> elements = riskFactors.elements.Where(factor => factor.provider == dataProviderString).ToList<RiskFactor>();
                if(dataProviderString.ToUpper() == "BLOOMBERG") elementProcessors.Add(new ElementProcessor(ProcessorLibrary.ProcessBloombergRiskFactors, elements));
            }
        }
        public static MarketDataElements<RiskFactor> GetRiskFactors()
        {
            // create and return deep copy of all base market risk factors
            return riskFactors.Clone();
        }
        private static void Check()
        {
            int nValidRiskFactors = 0;
            //
            // loop through all created risk factors for base market
            for (int i = 0; i < riskFactors.elements.Count; i++)
            {
                // extract risk factor to be investigated for valid value
                RiskFactor factor = riskFactors.elements[i];
                //
                // valid value inside risk factor should be double-typed converted to string, ex. "0.05328"
                // check validity of this value with Double
                // TryParse-method returning TRUE if string value can be converted to double
                double value = 0;
                bool isValid = Double.TryParse(factor.value, out value);
                if (isValid) nValidRiskFactors++;
                //
                // if value is not convertable to double, get user input for this value
                if (!isValid)
                {
                    while (true)
                    {
                        Console.Write(String.Format("Provide input for {0} >", factor.systemTicker));
                        bool validUserInput = Double.TryParse(Console.ReadLine(), out value);
                        if (validUserInput)
                        {
                            factor.value = value.ToString();
                            nValidRiskFactors++;
                            break;
                        }
                        else
                        {
                            // client is forced to set (at least technically) valid value
                            Console.WriteLine("Invalid value, try again");
                        }
                    }
                }
            }
        }
    }
}
//
//
//
//
// Configurations.cs
using System;
using System.Configuration;

namespace MarketDataProcess
{
    // static class for hosting configurations
    public static class Configurations
    {
        // readonly data for public sharing
        public static readonly string RiskFactorDataProviders;
        public static readonly string BaseMarketSourceDataFilePathName;
        public static readonly string BaseMarketResultDataFilePathName;
        //
        // private constructor will be called just before any configuration is requested 
        static Configurations()
        {
            // configuration strings are assigned to static class data members for easy access
            RiskFactorDataProviders = ConfigurationManager.AppSettings["RiskFactorDataProviders"].ToString();
            BaseMarketSourceDataFilePathName = ConfigurationManager.AppSettings["BaseMarketSourceDataFilePathName"].ToString();
            BaseMarketResultDataFilePathName = ConfigurationManager.AppSettings["BaseMarketResultDataFilePathName"].ToString();
        }
    }
}
//
//
//
//
// MarketDataElement.cs
using System;
using System.Collections.Generic;
using System.Linq;

namespace MarketDataProcess
{
    // generic template for all types of market data elements (risk factors, fixings)
    public class MarketDataElements<T> where T : ICloneable, new()
    {
        public List<T> elements = new List<T>();
        public void AddElement(T element)
        {
            elements.Add(element);
        }
        public MarketDataElements<T> Clone()
        {
            // create a deep copy of market data elements object
            MarketDataElements<T> clone = new MarketDataElements<T>();
            //
            // copy content for all elements into a list
            List<T> elementList = new List<T>();
            foreach (T element in elements)
            {
                elementList.Add((T)element.Clone());
            }
            clone.elements.AddRange(elementList);
            return clone;
        }
    }
    // risk factor as market data element
    public class RiskFactor : ICloneable
    {
        public string provider;
        public string systemTicker;
        public string vendorTicker;
        public string vendorField;
        public string divider;
        public string value;
        //
        public RiskFactor() { }
        public void Create(string stream)
        {
            List<string> fields = stream.Split(',').ToList<string>();
            this.provider = fields[0];
            this.systemTicker = fields[1];
            this.vendorTicker = fields[2];
            this.vendorField = fields[3];
            this.divider = fields[4];
            this.value = fields[5];
        }
        public object Clone()
        {
            RiskFactor clone = new RiskFactor();
            clone.provider = this.provider;
            clone.systemTicker = this.systemTicker;
            clone.vendorTicker = this.vendorTicker;
            clone.vendorField = this.vendorField;
            clone.divider = this.divider;
            clone.value = this.value;
            return clone;
        }
    }
    // fixing as market data element
    public class Fixing : ICloneable
    {
        public string provider;
        public string systemTicker;
        public string vendorTicker;
        public string vendorField;
        public string frequency;
        public string nYearsBack;
        public string divider;
        public string value;
        public Dictionary<string, string> timeSeries = new Dictionary<string, string>();
        //
        public Fixing() { }
        public void Create(string stream)
        {
            List<string> fields = stream.Split(',').ToList<string>();
            this.provider = fields[0];
            this.systemTicker = fields[1];
            this.vendorTicker = fields[2];
            this.vendorField = fields[3];
            this.frequency = fields[4];
            this.nYearsBack = fields[5];
            this.divider = fields[6];
            this.value = fields[7];
        }
        public object Clone()
        {
            Fixing clone = new Fixing();
            clone.provider = this.provider;
            clone.systemTicker = this.systemTicker;
            clone.vendorTicker = this.vendorTicker;
            clone.vendorField = this.vendorField;
            clone.divider = this.divider;
            clone.value = this.value;
            //
            // create deep copy of timeseries dictionary
            Dictionary<string, string> timeSeriesClone = new Dictionary<string, string>();
            foreach (KeyValuePair<string, string> kvp in this.timeSeries)
            {
                timeSeriesClone.Add(kvp.Key, kvp.Value);
            }
            clone.timeSeries = timeSeriesClone;
            return clone;
        }
    }
}
//
//
//
//
// ElementProcessor.cs
using System;
using System.Collections.Generic;

namespace MarketDataProcess
{
    // algorithm for creating market data element objects
    public delegate void Processor(dynamic marketDataElements);
    //
    // class for hosting data and algorithm
    public class ElementProcessor
    {
        private Processor taskProcessor;
        dynamic marketDataElements;
        public ElementProcessor(Processor taskProcessor, dynamic marketDataElements)
        {
            this.taskProcessor = taskProcessor;
            this.marketDataElements = marketDataElements;
        }
        public void Process()
        {
            taskProcessor.Invoke(marketDataElements);
        }
    }
}
//
//
//
//
// ProcessorLibrary.cs
using System;
using System.Collections.Generic;
using System.Linq;

namespace MarketDataProcess
{
    public static class ProcessorLibrary
    {
        public static void ProcessBloombergRiskFactors(dynamic marketDataElements)
        {
            List<RiskFactor> riskFactors = (List<RiskFactor>)marketDataElements;
            BBCOMMWrapper.BBCOMMDataRequest request;
            dynamic[, ,] result = null;
            string SYSTEM_DOUBLE = "System.Double";
            int counter = 0;
            //
            // group data list into N lists grouped by distinct bloomberg field names
            var dataGroups = riskFactors.GroupBy(factor => factor.vendorField);
            //
            // process each group of distinct bloomberg field names
            for (int i = 0; i < dataGroups.Count(); i++)
            {
                // extract group, create data structures for securities and fields
                List<RiskFactor> dataGroup = dataGroups.ElementAt(i).ToList<RiskFactor>();
                List<string> securities = new List<string>();
                List<string> fields = new List<string>() { dataGroup[0].vendorField };
                //
                // import securities into data structure feeded to bloomberg api
                for (int j = 0; j < dataGroup.Count; j++)
                {
                    securities.Add(dataGroup[j].vendorTicker);
                }
                //
                // create and use request object to retrieve bloomberg data
                request = new BBCOMMWrapper.ReferenceDataRequest(securities, fields);
                result = request.ProcessData();
                //
                // write retrieved bloomberg data into risk factor group data
                for (int k = 0; k < result.GetLength(0); k++)
                {
                    string stringValue;
                    dynamic value = result[k, 0, 0];
                    //
                    if (value.GetType().ToString() == SYSTEM_DOUBLE)
                    {
                        // handle output value with divider only if retrieved value is double
                        // this means that data retrieval has been succesfull
                        double divider = Convert.ToDouble(dataGroup[k].divider);
                        stringValue = (value / divider).ToString();
                        dataGroup[k].value = stringValue;
                        counter++;
                    }
                    else
                    {
                        // write non-double value (bloomberg will retrieve #N/A) if retrieved value is not double
                        stringValue = value.ToString();
                        dataGroup[k].value = stringValue;
                    }
                }
            }
        }
    }
}
//
//
//
//
// DummyBBCOMMWrapper.cs
using System;
using System.Collections.Generic;
using System.Linq;
using System.Text;
using System.Threading.Tasks;

namespace BBCOMMWrapper
{
    // abstract base class for data request
    public abstract class BBCOMMDataRequest
    {
        // input data structures
        protected List<string> securityNames = new List<string>();
        protected List<string> fieldNames = new List<string>();
        //
        // output result data structure
        protected dynamic[, ,] result;
        //
        public dynamic[, ,] ProcessData()
        {
            // instead of the actual Bloomberg market data, random numbers are going to be generated
            Random randomGenerator = new Random(Math.Abs(Guid.NewGuid().GetHashCode()));
            //
            for (int i = 0; i < securityNames.Count; i++)
            {
                for (int j = 0; j < fieldNames.Count; j++)
                {
                    result[i, 0, j] = randomGenerator.NextDouble();
                }
            }
            return result;
        }
    }
    //
    // concrete class implementation for processing reference data request
    public class ReferenceDataRequest : BBCOMMDataRequest
    {
        public ReferenceDataRequest(List<string> bloombergSecurityNames,
            List<string> bloombergFieldNames)
        {
            securityNames = bloombergSecurityNames;
            fieldNames = bloombergFieldNames;
            result = new dynamic[securityNames.Count, 1, fieldNames.Count];
        }
    }
}
//
//
//
//
// TextFileHandler.cs
using System;
using System.Collections.Generic;
using System.IO;

namespace MarketDataProcess
{
    public static class TextFileHandler
    {
        public static void Read(string filePathName, List<string> output)
        {
            // read file content into list
            StreamReader reader = new StreamReader(filePathName);
            while (!reader.EndOfStream)
            {
                output.Add(reader.ReadLine());
            }
            reader.Close();
        }
        public static void Write(string filePathName, List<string> input, bool append)
        {
            // write text stream list to file
            StreamWriter writer = new StreamWriter(filePathName, append);
            input.ForEach(it => writer.WriteLine(it));
            writer.Close();
        }
        public static void Write(string filePathName, string input, bool append)
        {
            // write bulk text stream to file
            StreamWriter writer = new StreamWriter(filePathName, append);
            writer.Write(input);
            writer.Close();
        }
    }
}

Saturday, March 5, 2016

C# : Using XmlSerializer for creating (storing) objects from (to) XML file


This time, I wanted to share a cool mechanism for handling object presentation between object instance and XML file. This mechanism can be found in System.Xml.Serialization namespace. In short, when using XmlSerializer we can create object instance directly from XML file and store object blueprint information to XML file to be used whenever needed.


Real-life design scheme


Assume we have some state-of-the-art analytic calculation engine, into which we feed a lot of different transactions and market scenario data in the first place. When the engine is up and running, we can simply give any specific calculation task object to be processed for this engine. One Task object will simply define a specific set of parameters, such as

  • Calculation task name
  • What kind of transactions will be selected?
  • In what kind of market scenario those selected transactions will be valued?
  • What kind of output values will be calculated for each transaction?

Obviously, the beef is really in handling all required configuration parameters for all calculation tasks in an efficient manner. For this purpose, we need to be able to create calculation task instances from some source. Blueprints for all task objects can be stored into XML files, from which the actual objects are going to be created by XmlSerializer to be processed by the engine.


Bridge over troubled water


For the purposes mentioned above, I came up with an idea of generic ObjectXMLHandler<T> class for handling Object/XML transformations for any type of object, not only for Task object which has been used in this example. Behind the scenes, this class is nothing more but a wrapper for XmlSerializer, which can create (store) a list of objects from (to) XML files.

For storing object blueprints into XML file (Serialize), the class client will give a list of object instances, a list of file names to be used and a path name for a specific target folder. Below is a screenshot of one Task object blueprint XML file, created by ObjectXMLHandler.


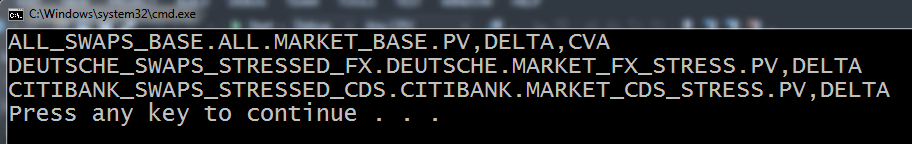
For creating objects from XML file (Deserialize), the class client will only give a path name for a specific target folder, in which all object blueprints are stored in XML files. When calling this method, the class will return a list of object instances (having type of T) for its client. Below is a screenshot of all three Task object instances which have been created from XML files by ObjectXMLHandler.


Personally, I find XmlSerialization class to be extremely useful for the schemes like the one presented in here. It will completely liberate me from writing my own XML handlers for such cases.

A small dark cloud within this overwhelming joy is the fact, that this presented XmlSerializer class can only handle member data which has been defined to be public. For other cases, I would recommend to dig deeper into implementing IXmlSerializable interface, found in the same namespace.

Thanks for reading my blog. I hope you have got some useful ideas for your own programs.


The Program


Create a new project consisting of three CS files (Program, Task, ObjectXMLHandler). CopyPaste the following program into corresponding CS files.

// Program.cs content
using System;
using System.Collections.Generic;

namespace XMLTester
{
    class Program
    {
        private static string FilePathName = @"C:\temp\Tasks\";
        //        
        static void Main(string[] args)
        {
            try
            {
                // create instance of ObjectXMLHandler for Task type
                ObjectXMLHandler<Task> handler = new ObjectXMLHandler<Task>();
                //
                // A. SERIALIZING (object to XML)
                // create a list of required XML file names
                List<string> fileNames = new List<string>() 
                { 
                    "TaskOne.xml", 
                    "TaskTwo.xml", 
                    "TaskThree.xml" 
                };
                // create a list of calculation task configuration objects
                List<Task> tasks = new List<Task>() 
                { 
                    new Task("ALL_SWAPS_BASE", "ALL", "MARKET_BASE", "PV,DELTA,CVA"),
                    new Task("CITIBANK_SWAPS_STRESSED_CDS", "CITIBANK", "MARKET_CDS_STRESS", "PV,DELTA"), 
                    new Task("DEUTSCHE_SWAPS_STRESSED_FX", "DEUTSCHE", "MARKET_FX_STRESS", "PV,DELTA")
                };
                // write task objects to XML files
                handler.Serialize(tasks, fileNames, FilePathName);
                //
                // B. DE-SERIALIZING (XML to object)
                // create task objects from XML files and print task configuration string
                tasks = handler.Deserialize(FilePathName);
                tasks.ForEach(task => Console.WriteLine(task.ToString()));
            }
            catch (Exception ex)
            {
                Console.WriteLine(ex.Message);
            }
        }
    }
}
//
//
//
// Task.cs content
using System;

namespace XMLTester
{
    /// <summary>
    /// Class for administrating calculation task parameters. 
    /// </summary>
    public class Task
    {
        public string taskName;
        public string tradeSelection;
        public string marketSelection;
        public string calculationOutput;
        //
        /// <summary>
        /// Default constructor is required by XMLSerializer.
        /// </summary>
        public Task()
        {
            //
        }
        /// <summary>
        /// Parameter constructor for creating one calculation task object.
        /// </summary>
        public Task(string taskName, string tradeSelection, 
            string marketSelection, string calculationOutput)
        {
            this.taskName = taskName;
            this.tradeSelection = tradeSelection;
            this.marketSelection = marketSelection;
            this.calculationOutput = calculationOutput;
        }
        /// <summary>
        /// Get configuration string for calculation task.
        /// </summary>
        public override string ToString()
        {
            return String.Format("{0}.{1}.{2}.{3}", 
                taskName, tradeSelection, marketSelection, calculationOutput);
        }
    }
}
//
//
//
// ObjectXMLHandler.cs content
using System;
using System.Collections.Generic;
using System.IO;
using System.Xml.Serialization;

namespace XMLTester
{
    /// <summary>
    /// Generic template class for handling conversion 
    /// between object and XML presentation.
    /// </summary>
    public class ObjectXMLHandler<T>
    {
        private XmlSerializer serializer = null;
        private Stream stream = null;
        //
        /// <summary>
        /// Parameter constructor for creating an instance. 
        /// </summary>
        public ObjectXMLHandler()
        {
            serializer = new XmlSerializer(typeof(T));
        }
        /// <summary>
        /// Convert a list of objects of type T into XML files. 
        /// </summary>
        public void Serialize(List<T> objects, List<string> fileNames, string folderPathName)
        {
            if (objects.Count != fileNames.Count) 
                throw new Exception("objects.Count != fileNames.Count");
            //
            int counter = 0;
            foreach (T t in objects)
            {
                stream = File.Create(Path.Combine(folderPathName, String.Concat(fileNames[counter])));
                serializer.Serialize(stream, t);
                stream.Close();
                counter++;
            }
        }
        /// <summary>
        /// Convert XML files in specific folder into a list of objects of type T.
        /// </summary>
        public List<T> Deserialize(string folderPathName)
        {
            List<T> objects = new List<T>();
            foreach (string t in Directory.GetFiles(folderPathName))
            {
                stream = File.OpenRead(t);
                objects.Add((T)serializer.Deserialize(stream));
                stream.Close();
            }
            return objects;
        }
    }
}

Saturday, January 23, 2016

QuantLib : Simulating HW1F paths using PathGenerator

Monte Carlo is bread and butter for so many purposes. Calculating payoffs for complex path-dependent products or simulating future exposures for calculating CVA are two excellent examples. The big question is always how to do this efficiently. Designing, implementing and setting up any non-trivial in-house tool to do the job is everything but not a simple afternoon exercise with a cup of coffee and Excel. Fortunately, QuantLib is offering pretty impressive tools for simulating stochastic paths. This time, I wanted to share the results of my woodshedding with QL PathGenerator class. 


Parallel lives


In order to really appreciate the tools offered by QL, let us see the results first. Some simulated paths using Hull-White One-Factor model are shown in the picture below.


If one really want to start from the scratch, there are a lot of things to do in order to produce these paths on a flexible manner and handling all the complexities of the task at the same time. Thanks for QL, those days are finally over.


Legoland


Setting up desired Stochastic Process and Gaussian Sequence Generator are two main components needed in order to get this thing up and running.

Along with required process parameters (reversion speed and rate volatility), HullWhiteProcess needs Handle to YieldTermStructure object, such as PiecewiseYieldCurve, as an input.

 // create Hull-White one-factor stochastic process
 Real reversionSpeed = 0.75;
 Real rateVolatility = 0.015;
 boost::shared_ptr<StochasticProcess1D> HW1F(
  new HullWhiteProcess(curveHandle, reversionSpeed, rateVolatility));

For this example, I have used my own PiecewiseCurveBuilder template class in order to make curve assembling a bit more easier. It should be noted, that the menu of one-dimensional stochastic processes in QL is covering pretty much all standard processes one needs for different asset classes.

Gaussian Sequence Generator (GSG) is assembled by using the following three classes : uniform random generator (MersenneTwisterUniformRng),  distributional transformer (CLGaussianRng) and RandomSequenceGenerator.

 // type definition for complex declaration
 typedef RandomSequenceGenerator<CLGaussianRng<MersenneTwisterUniformRng>> GSG;
 //
 // create mersenne twister uniform random generator
 unsigned long seed = 28749;
 MersenneTwisterUniformRng generator(seed);
 //
 // create gaussian generator by using central limit transformation method
 CLGaussianRng<MersenneTwisterUniformRng> gaussianGenerator(generator);
 //
 // define maturity, number of steps per path and create gaussian sequence generator
 Time maturity = 5.0;
 Size nSteps = 1250;
 GSG gaussianSequenceGenerator(nSteps, gaussianGenerator);
 //
 // create path generator using Hull-White process and gaussian sequence generator
 PathGenerator<GSG> pathGenerator(HW1F, maturity, nSteps, gaussianSequenceGenerator, false);

Finally, PathGenerator object is created by feeding desired process and generator objects in constructor method, along with the other required parameters (maturity, number of steps). After this, PathGenerator object is ready for producing stochastic paths for its client.

The program


Example program will first create relinkable handle to PiecewiseYieldCurve object. Remember to include required files into your project from here. After this, the program creates HW1F process object and Gaussian Sequence Generator object, which are feeded into PathGenerator object. Finally, the program creates 20 stochastic paths, which are saved into Matrix object and ultimately being printed into text file for further analysis (Excel chart).

#include "PiecewiseCurveBuilder.cpp"
#include <fstream>
#include <string>
//
// type definition for complex declaration
typedef RandomSequenceGenerator<CLGaussianRng<MersenneTwisterUniformRng>> GSG;
//
// function prototypes
RelinkableHandle<YieldTermStructure> CreateCurveHandle(Date settlementDate);
void PrintMatrix(const Matrix& matrix, std::string filePathName);
//
int main()
{
 // request handle for piecewise USD Libor curve
 Date tradeDate(22, January, 2016);
 Settings::instance().evaluationDate() = tradeDate;
 Date settlementDate = UnitedKingdom().advance(tradeDate, 2, Days);
 RelinkableHandle<YieldTermStructure> curveHandle = CreateCurveHandle(settlementDate);
 //
 // create Hull-White one-factor stochastic process
 Real reversionSpeed = 0.75;
 Real rateVolatility = 0.015;
 boost::shared_ptr<StochasticProcess1D> HW1F(
  new HullWhiteProcess(curveHandle, reversionSpeed, rateVolatility));
 //
 // create mersenne twister uniform random generator
 unsigned long seed = 28749;
 MersenneTwisterUniformRng generator(seed);
 //
 // create gaussian generator by using central limit transformation method
 CLGaussianRng<MersenneTwisterUniformRng> gaussianGenerator(generator);
 //
 // define maturity, number of steps per path and create gaussian sequence generator
 Time maturity = 5.0;
 Size nSteps = 1250;
 GSG gaussianSequenceGenerator(nSteps, gaussianGenerator);
 //
 // create path generator using Hull-White process and gaussian sequence generator
 PathGenerator<GSG> pathGenerator(HW1F, maturity, nSteps, gaussianSequenceGenerator, false);
 //
 // create matrix container for 20 generated paths
 Size nColumns = 20;
 Matrix paths(nSteps + 1, nColumns);
 for(unsigned int i = 0; i != paths.columns(); i++)
 {
  // request a new stochastic path from path generator
  QuantLib::Sample<Path> path = pathGenerator.next();
  //
  // save generated path into container
  for(unsigned int j = 0; j != path.value.length(); j++)
  {
   paths[j][i] = path.value.at(j);
  }
 }
 // finally, print matrix content into text file
 PrintMatrix(paths, "C:\\temp\\HW1F.txt");
 return 0;
}
//
void PrintMatrix(const Matrix& matrix, std::string filePathName)
{
 // open text file for input, loop through matrix rows
 std::ofstream file(filePathName);
 for(unsigned int i = 0; i != matrix.rows(); i++)
 {
  // concatenate column values into string separated by semicolon
  std::string stream;
  for(unsigned int j = 0; j != matrix.columns(); j++)
  {
   stream += (std::to_string(matrix[i][j]) + ";");
  }
  // print string into text file
  file << stream << std::endl;
 }
 // close text file
 file.close();
}
//
RelinkableHandle<YieldTermStructure> CreateCurveHandle(Date settlementDate)
{
 // create curve builder for piecewise USD Libor swap curve
 PiecewiseCurveBuilder<USDLibor> USDCurveBuilder(settlementDate, 
  UnitedKingdom(), Annual, Thirty360());
 //
 // add quotes directly into curve builder
 USDCurveBuilder.AddDeposit(0.0038975, 1 * Weeks);
 USDCurveBuilder.AddDeposit(0.004295, 1 * Months);
 USDCurveBuilder.AddDeposit(0.005149, 2 * Months);
 USDCurveBuilder.AddDeposit(0.006127, 3 * Months);
 USDCurveBuilder.AddFRA(0.008253, 3 * Months, 3 * Months);
 USDCurveBuilder.AddFRA(0.009065, 6 * Months, 3 * Months);
 USDCurveBuilder.AddFRA(0.01059, 9 * Months, 3 * Months);
 USDCurveBuilder.AddSwap(0.011459, 2 * Years);
 USDCurveBuilder.AddSwap(0.013745, 3 * Years);
 USDCurveBuilder.AddSwap(0.015475, 4 * Years);
 USDCurveBuilder.AddSwap(0.016895, 5 * Years);
 USDCurveBuilder.AddSwap(0.01813, 6 * Years);
 USDCurveBuilder.AddSwap(0.019195, 7 * Years);
 USDCurveBuilder.AddSwap(0.020115, 8 * Years);
 USDCurveBuilder.AddSwap(0.020905, 9 * Years);
 USDCurveBuilder.AddSwap(0.021595, 10 * Years);
 USDCurveBuilder.AddSwap(0.0222, 11 * Years);
 USDCurveBuilder.AddSwap(0.022766, 12 * Years);
 USDCurveBuilder.AddSwap(0.0239675, 15 * Years);
 USDCurveBuilder.AddSwap(0.025105, 20 * Years);
 USDCurveBuilder.AddSwap(0.025675, 25 * Years);
 USDCurveBuilder.AddSwap(0.026015, 30 * Years);
 USDCurveBuilder.AddSwap(0.026205, 40 * Years);
 USDCurveBuilder.AddSwap(0.026045, 50 * Years);
 //
 // return relinkable curve handle
 return USDCurveBuilder.GetCurveHandle();
}

Thanks for reading my blog.

-Mike